

Executive Overview
Following a sluggish start to the year, the global electric vehicle (EV) market experienced a formidable resurgence in the second quarter of 2026. Data compiled by the International Energy Agency (IEA) reveals that worldwide EV sales vaulted 35% in Q2 compared to the first three months of the year, setting historic quarterly records in 50 countries.
This robust expansion stands in stark contrast to the broader automotive sector. Overall global car sales contracted by approximately 5% year-over-year during the first half of 2026. Persisting economic headwinds, high fuel prices, and sudden policy shifts in major economies like the United States and China dampened consumer enthusiasm for traditional internal combustion engine (ICE) vehicles. Yet, even as legacy automotive segments stumbled, consumer appetite for plug-in options—encompassing both battery electric vehicles (BEVs) and plug-in hybrid electric vehicles (PHEVs)—accelerated across nearly every inhabited continent.
Buoyed by this unexpected resilience, the IEA has revised its global forecast upward. Electric vehicles are now projected to account for 29% of all new car sales worldwide by the end of 2026, marking a one-percentage-point increase over the agency’s previous projections published in May.
Nevertheless, the trajectory of the global EV transition is far from uniform. While emerging economies in Southeast Asia, Latin America, and South Asia are rapidly expanding their charging footprints and consumer adoption, key legacy markets face severe domestic headwinds. In the US, the sudden removal of federal incentives has choked off demand, while China grapples with plateauing domestic sales paired with an unprecedented production surplus exceeding one million unsold electric vehicles ready for export.
Detailed Chronology: The First Half of 2026
The opening half of 2026 has been characterized by sharp contrasts, dividing the global automotive landscape into regions of aggressive electrification and zones of policy-induced stagnation.
Q1 2026: The Sluggish Foundation
The year began on precarious footing. Throughout January and February, global EV sales suffered from a contraction largely concentrated in two of the world’s most critical automotive hubs: the United States and China. In the US, the retroactive hangover from the September 2025 termination of federal EV tax credits began to bite hard. Concurrently, weakening consumer confidence and macroeconomic tightening in China slowed what had previously been an unstoppable upward trajectory in the world’s largest automotive market.
Automakers found themselves adjusting production targets downward as dealers reported bloated inventories of unsold electric models. Analysts warned that the golden era of unbridled EV growth might be encountering a permanent ceiling.
Q2 2026: The Global Rebound
That pessimism dissolved by the end of May. As spring turned to summer, global consumer demand rebounded with unexpected ferocity. Q2 sales surged 35% over the Q1 baseline, propelled by localized policy incentives in Europe, aggressive pricing strategies from Asian manufacturers, and escalating anxieties regarding traditional fossil fuel volatility.
By the close of June, over 90 countries had registered positive year-over-year EV sales growth for the first half of 2026. Standout nations—including Australia, Brazil, India, South Korea, and Vietnam—reported that sales figures from March through June were roughly double those recorded during the exact same window in 2025.
Crucially, this growth was no longer driven solely by early adopters in wealthy Western European capitals or Tier-1 Chinese mega-cities. Instead, it was catalyzed by a democratization of EV technology, marked by the arrival of high-value, highly affordable imported models into developing markets.
Supporting Context & Metrics: Regional Divergence and Market Realities
To understand the 2026 global EV landscape, one must analyze the complex interplay between government policy, manufacturing scale, and shifting geopolitical trade dynamics.
The Rise of Emerging Markets
While the US and parts of Europe navigate political friction surrounding green energy mandates, emerging markets are sprinting ahead. Developing economies are increasingly viewing electrification not merely through an environmental lens, but as an urgent matter of national energy security and economic insulation.
Countries in Latin America and Southeast Asia have introduced targeted tax exemptions, import tariff reductions for clean vehicles, and public-private investments in charging infrastructure. These measures have lowered the barrier to entry for everyday consumers, transforming EVs from luxury novelty items into practical, cost-effective daily drivers.
China’s Domestic Plateau and Export Tsunami
China remains the epicenter of the global EV supply chain, yet its domestic market is undergoing a structural maturation. The IEA projects that Chinese EV sales will stagnate year-over-year for the first time this decade as the wider national car market cools. However, this plateau must be viewed in context: more than 60% of all new passenger vehicles sold in China throughout 2026 are still expected to be electric—an all-time high penetration rate.
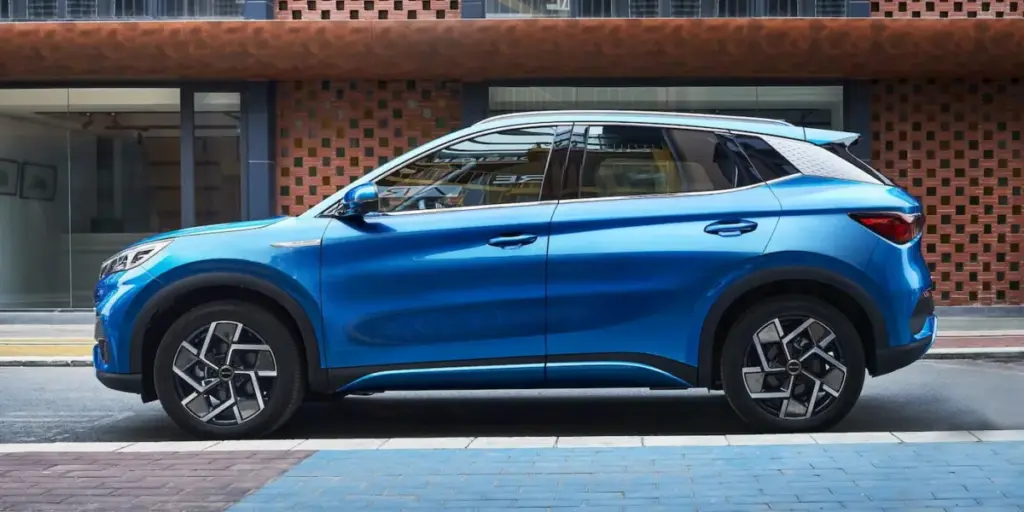
Unable to absorb its immense domestic manufacturing output entirely within its own borders, China’s industrial apparatus has pivoted aggressively toward export markets. During the first six months of 2026 alone, Chinese automakers exported nearly as many electric vehicles as they did during the entirety of 2025.
According to IEA estimates, approximately one-third of these exported vehicles remain unsold at international destination ports. Combined with inventory spillover from late 2025, there are currently more than 1 million Chinese-made electric cars sitting in global supply chains, actively looking for buyers.
This unprecedented inventory surplus presents a double-edged sword for the global market:
- For Consumers: It guarantees an influx of competitively priced, technologically advanced models that will drive down prices and accelerate adoption in emerging economies.
- For Legacy Automakers: It intensifies the competitive pressure on traditional original equipment manufacturers (OEMs) in Europe and the Americas, many of which are struggling to engineer profitable EVs at price points that can compete with Chinese manufacturing efficiencies.
Industry analysts emphasize that China and other emerging economies are projected to account for roughly 60% of total global car demand over the next decade. Consequently, automakers that successfully secure market share in these developing regions are positioned to dominate the global automotive industry for generations to come.
The US Policy Vacuum
Conversely, the United States has engineered a domestic slowdown through deliberate policy contraction. Following the Trump administration’s decision to sunset federal EV tax credits in September 2025—alongside a significant loosening of federal fuel-economy standards—automakers and consumers lost their primary financial catalysts for electrification.
Unsurprisingly, US EV demand has plummeted from its projected growth trajectory. Without federal backing, domestic adoption has become heavily dependent on patchy state-level incentives and corporate fleet mandates, leaving the US market increasingly isolated from the rapid electrification sweeping the rest of the industrialized world.
Fossil Fuel Volatility and Energy Security
External geopolitical shocks have injected further urgency into the transition away from internal combustion engines. Ongoing conflicts in the Middle East have reignited acute anxiety regarding global energy security and crude oil price volatility.

Road transport accounts for nearly half of global oil consumption. Every geopolitical flashpoint in oil-producing regions directly exposes drivers and national treasuries to sudden fuel price spikes and supply chain disruptions. Nations that rely heavily on imported petroleum are finding that accelerated EV adoption is no longer an optional environmental goal, but a critical pillar of macroeconomic defense.
Official Statements and Industry Analysis
The release of the updated IEA analysis has triggered widespread commentary across the international energy and automotive sectors.
Speaking on the resilience of the sector, energy economists highlighted that consumer demand has proven structurally sound despite localized setbacks. "When given access to affordable models and reliable charging, consumers worldwide are voting with their wallets in favor of electric mobility," noted an energy market analyst tracking the IEA data. "The stagnation we see in specific policy-constrained markets like the US is an aberration, not a global rule."
Regarding the surplus of Chinese EV inventory, trade experts warn that traditional manufacturing strongholds must rethink their strategies. "You cannot legislate away global manufacturing competitiveness," said an international trade researcher. "With over a million unsold Chinese EVs positioned globally, protectionist tariffs may buy legacy automakers a brief window of time, but they do not solve the fundamental challenge of cost structure and innovation speed."
The IEA itself concluded its mid-year assessment with a clear policy warning. The future pace of the global energy transition will depend heavily on the legislative and financial choices made by national governments. States can choose to shield their citizens from volatile oil markets through proactive infrastructure and consumer support, or they can follow the path of least resistance—rescinding support just as the global clean-transportation paradigm accelerates past them.
Future Outlook
Looking ahead to the remainder of 2026 and into the next decade, the trajectory of the automotive industry is clear, even if unevenly distributed.
- The 29% Milestone: With the IEA officially upgrading its global market share expectation to 29% for 2026, the transition past the early-adopter chasm is firmly underway. Mass-market normalization is accelerating faster than predicted at the start of the decade.
- Infrastructure Evolution: Markets that weathered the early infrastructure bottlenecks are now entering advanced deployment phases. In the US, for instance, localized charging networks are transitioning toward "Charging 2.0" standards—focusing on high reliability, plug-and-charge convenience, and ultra-fast five-minute replenishment times to win back skeptical consumers.
- The Battle for Emerging Markets: As mature markets in North America and parts of Europe navigate political hurdles, the real battleground for automotive supremacy has shifted decisively to the Global South. The absorption of China’s 1-million-plus surplus inventory across Latin America, South Asia, and Southeast Asia will likely redraw the global automotive map by 2030.
Ultimately, the first half of 2026 has demonstrated that the global transition to electric mobility possesses profound structural momentum. While individual nations may attempt to slow the tide through policy rollbacks, the convergence of falling battery costs, surging export capacity, and volatile fossil fuel markets ensures that the future of personal transport belongs firmly to the plug.



