Executive Overview
The United States energy storage market is currently surging at an unprecedented pace. Across the country, massive battery installations are going online at record-shattering frequencies, performing the heavy lifting required to shore up an aging national electrical grid. These utility-scale batteries are vital for increasing reliability, mitigating peak-load stress, and dramatically cutting carbon emissions by smoothing out the notoriously intermittent supply of wind and solar power. Without this massive influx of storage capacity, America’s ambitious clean-energy transition would risk stalling out under its own weight.
Yet, this monumental green expansion is built upon a profound geopolitical irony: it has relied almost entirely on cheap, high-quality, and readily available Chinese batteries. For years, Beijing has dominated the global clean-tech manufacturing ecosystem, producing solar panels, inverters, and battery cells at scales and prices that Western competitors have struggled to match.
Recognizing the acute strategic vulnerability of depending on a primary geopolitical rival for critical energy infrastructure, Washington has spent the past several years aggressively attempting to decouple its supply chains. This legislative and economic friction culminated in late August when the administration issued a sweeping executive order declaring a national emergency. The directive effectively bans Chinese-made batteries from being utilized in the nation’s bulk-power grid systems.
This high-stakes maneuver highlights a foundational policy paradox confronting modern industrial democracies: How far should governments go to sever ties with dominant, low-cost foreign tech suppliers in order to stimulate domestic manufacturing, even when doing so drives up costs, stalls green deployment, and threatens near-term climate targets?
As the energy sector digests the profound implications of this latest executive order, developers, analysts, and policymakers are left grappling with an uncertain future. The move promises to reshape the American energy landscape, pitting the imperatives of national security against the economic realities of the energy transition.
Detailed Chronology: From Economic Incentives to Outright Bans
The United States’ campaign to purge Chinese influence from its battery supply chain has evolved through distinct phases over the past several years, shifting from subtle financial nudges to blunt economic force.
The 2022 Inflation Reduction Act: Rewriting the Rules of Origin
The opening salvo in Washington’s modern supply-chain decoupling strategy arrived with the passage of the landmark Inflation Reduction Act (IRA) in August 2022. While widely celebrated for pumping hundreds of billions of dollars into domestic clean energy, the legislation introduced stringent, highly complex localization requirements.
Under the original IRA framework, electric vehicle and energy storage tax credits were explicitly tied to the geographic origin of a battery’s components. The rules stipulated strict thresholds for where critical minerals—such as lithium, cobalt, and nickel—had to be mined, processed, or recycled. Furthermore, they mandated specific regional quotas for where the actual battery cells and structural packs could be assembled. By restricting eligibility, the policy sought to artificially inflate the cost-competitiveness of nascent domestic technologies against cheap Chinese imports.
The 2025 Framework Update and New Thresholds
As the industrial landscape shifted, the federal government refined these criteria. In 2025, the tax credit framework underwent a comprehensive makeover designed to tighten loopholes and accelerate domestic production milestones.
Under updated legislative guidance, the rules became even more uncompromising. Beginning in 2026, the law dictates that a staggering 55% of the total material cost used in new energy storage projects must originate from outside of China and other designated restricted nations. Projects that fail to clear this localized content hurdle face total disqualification from lucrative federal tax credits, effectively pulling the rug out from under developers who rely on foreign supply chains to maintain project margins.
The Section 301 Tariff Escalation
Simultaneously, the federal government deployed traditional trade protectionism. In January, import duties on foreign-made batteries—enforced under Section 301 tariffs—saw a dramatic escalation. Tariffs leaped from a modest 7.5% to a punishing 25%, instantly squeezing import margins and signaling a rapidly closing window for cost-effective Chinese hardware procurement.
The August 2026 Executive Order: The National Emergency Declaration
Despite tax credit restrictions and steep tariffs, developers continued finding ways to procure cost-effective Chinese components to meet skyrocketing grid-storage demand. Frustrated by this persistent reliance, the administration took a much more radical, interventionist step in late August.
Citing severe vulnerabilities in the nation’s critical infrastructure, the White House issued an executive order declaring a national emergency to secure the United States bulk-power system. This sweeping directive explicitly prohibits the installation of "any foreign-produced bulk-power system electric equipment" deemed to present an unacceptable national security risk.
While the order casts a wide net over critical hardware, it specifically targets battery energy storage systems (BESS), alongside essential balance-of-system components like high-voltage inverters and grid transformers. Rather than relying purely on market-based mechanisms like tariffs or tax penalties, the August 2026 executive order established an absolute regulatory firewall.
Supporting Context & Metrics: The Domestic Landscape and Market Fallout
The sudden imposition of a de facto ban on Chinese storage tech has sent immediate shockwaves through the energy sector, triggering a complex chain reaction of market corrections, supply chain pivots, and regulatory anxiety.
Near-Term Project Delays and the Threat of Cancellations
According to recent market analyses from BloombergNEF (BNEF), the executive order is poised to significantly decelerate the deployment of grid-connected energy storage projects in the near term. Energy developers are currently navigating a cloud of profound regulatory ambiguity, forcing many to pause construction and procurement while waiting for formal compliance guidance.
"An outright ban was a bit of a surprise, and it does create a bit of concern for domestic players in the US," notes Shan Tomouk, energy storage and energy lead for Benchmark Mineral Intelligence.
The Department of Energy is expected to release detailed implementation guidance before the end of the year. Depending on how stringently these rules are written, project developers may be forced into frantic searches for alternative cell suppliers—sourcing either from domestic gigafactories or alternative international markets such as South Korea or Japan.
However, these alternatives come with severe economic friction. Isshu Kikuma, an energy storage analyst at BloombergNEF, warns that these substitute inputs will inevitably be far more expensive than their Chinese counterparts.
"Worst case, those projects could get canceled," Kikuma cautions, pointing out that razor-thin development margins cannot always absorb sudden, steep spikes in hardware acquisition costs.
The Retroactive Dilemma for Existing Infrastructure
Perhaps the most legally and operationally contentious aspect of the new executive order is its technical scope. Strictly interpreted, the mandate applies not just to greenfield developments, but potentially to existing energy storage plants already integrated into the grid.
However, industry experts agree that pulling the plug on operational assets is a practical impossibility. Because the vast majority of utility-scale storage systems currently operating on the US grid rely heavily on Chinese battery cells and inverters, enforcing the order retroactively to the letter would mean stripping out a massive share of the nation’s total installed storage capacity. Doing so would instantly destabilize regional grids, spike consumer electricity prices, and reverse years of reliability gains.
Instead, regulatory agencies are expected to grandfather in existing installations while applying the iron fist of the ban exclusively to future projects and major component replacements.
The 2030 Horizon: Can Domestic Manufacturing Fill the Void?
Looking toward the medium and long term, proponents of the ban argue that American manufacturing muscle will step up to fill the void. Current industrial projections suggest the United States could theoretically achieve self-sufficiency in battery production by approximately 2030.
Yet, this timeline is fraught with caveats. Analysts note that while nameplate factory capacity may technically exist by the end of the decade, operational friction, supply chain bottlenecks for precursor materials, and underutilized assembly lines mean that true domestic supply sufficiency may not comfortably match national demand until well into the 2030s.
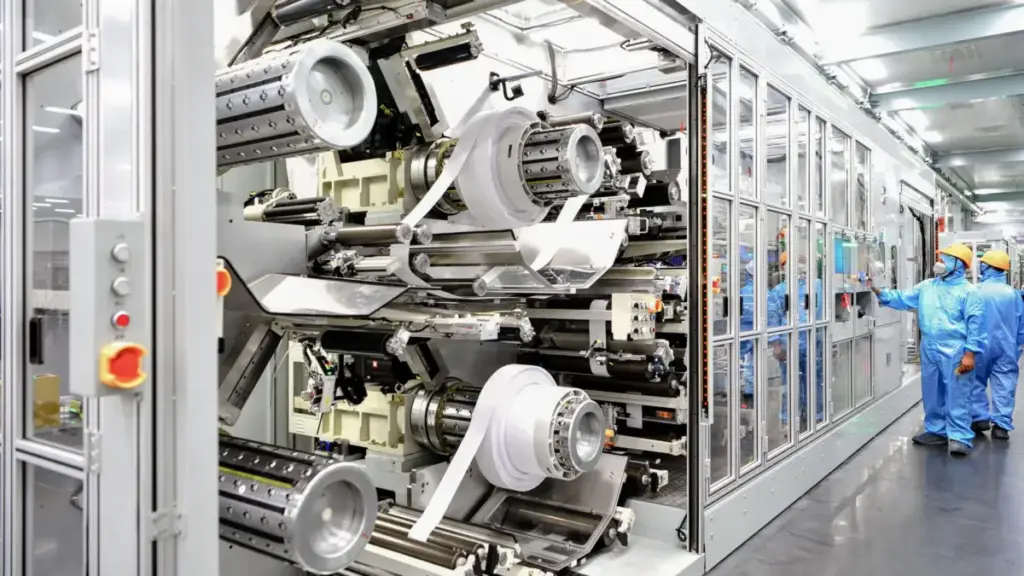
Interestingly, an unexpected economic savior has emerged to help bridge this manufacturing gap: the cooling electric vehicle (EV) market. As consumer adoption rates for passenger EVs have experienced a temporary plateau, automotive battery manufacturers have faced excess capacity. In a clever industrial pivot, several major players are actively retooling facilities originally engineered for automotive battery packs to produce stationary energy storage cells instead.
New domestic gigafactories backed by major industrial heavyweights—including LG Energy Solutions, Samsung SDI, Ford, and SK On—are slated to come online or significantly ramp up production over the next year.
Yet, this domestic renaissance comes with an unavoidable financial sting. Batteries manufactured within the United States remain significantly more expensive than those produced in mature Chinese facilities. Even pivoting toward allied international suppliers, such as South Korean firms, incurs a considerable cost premium that will ultimately be borne by utility ratepayers and taxpayers.
Official Statements and Industry Perspectives
The policy pivot has exposed deep philosophical and operational divisions within the American energy economy, sparking fierce debates between national security hawks, green energy advocates, and industrial stakeholders.
The National Security Imperative
Defenders of the administration’s actions argue that the risks of inaction far outweigh the short-term economic pain. From the perspective of national security strategists, allowing a geopolitical adversary to maintain deep operational control over the hardware underpinning America’s critical electrical grid is an unacceptable strategic gamble.
Bulk-power systems, transformers, and large-scale battery management systems rely on complex software and firmware interfaces. Policymakers contend that potential vulnerabilities—such as remote shut-down capabilities or backdoors embedded in foreign-manufactured inverters and battery management systems—pose a clear and present danger to national sovereignty and public safety during a geopolitical crisis.
The Clean Energy and Economic Reality
Conversely, clean energy trade associations and utility executives have sounded alarms over the economic collateral damage. Transitioning the American power grid away from fossil fuels requires moving at a historic speed and scale. By artificially restricting access to the most efficient, cost-effective storage technologies available on the global market, policymakers are deliberately compounding the difficulty of achieving federal decarbonization mandates.
Furthermore, industry analysts point out that China’s commanding lead in clean tech is not an accidental byproduct of cheap labor, but the result of decades of sustained government investment, targeted research, and specialized manufacturing experience. Attempting to replicate that deeply integrated industrial ecosystem overnight through punitive executive decrees risks throttling the very energy transition the government claims to support.
Future Outlook: Navigating the Delicate Balance
As the United States charts its course toward an independent energy future, the nation finds itself walking a precarious tightrope between two competing imperatives.
On one side lies the urgent necessity to aggressively slash carbon emissions and stabilize power grids in the face of accelerating climate disruption—goals made vastly easier and cheaper by embracing the global marketplace and leveraging affordable Chinese technology. On the other side sits the imperative of economic resilience and national security, demanding that a great power control the foundational supply chains of its critical infrastructure.
The coming months will prove definitive. When the Department of Energy issues its final guidance on the executive order before the end of the year, developers will finally learn the precise boundaries of compliance. Whether the market can successfully absorb these seismic shifts—pivoting toward higher-cost domestic production without triggering widespread project cancellations—will determine the trajectory of the American clean energy transition for the next decade.
Ultimately, the great battery showdown of 2026 is much more than a localized regulatory dispute. It serves as a defining stress test for modern globalization, illustrating the profound friction that occurs when the unstoppable force of the global energy transition collides with the immovable object of geopolitical competition.