Executive Overview
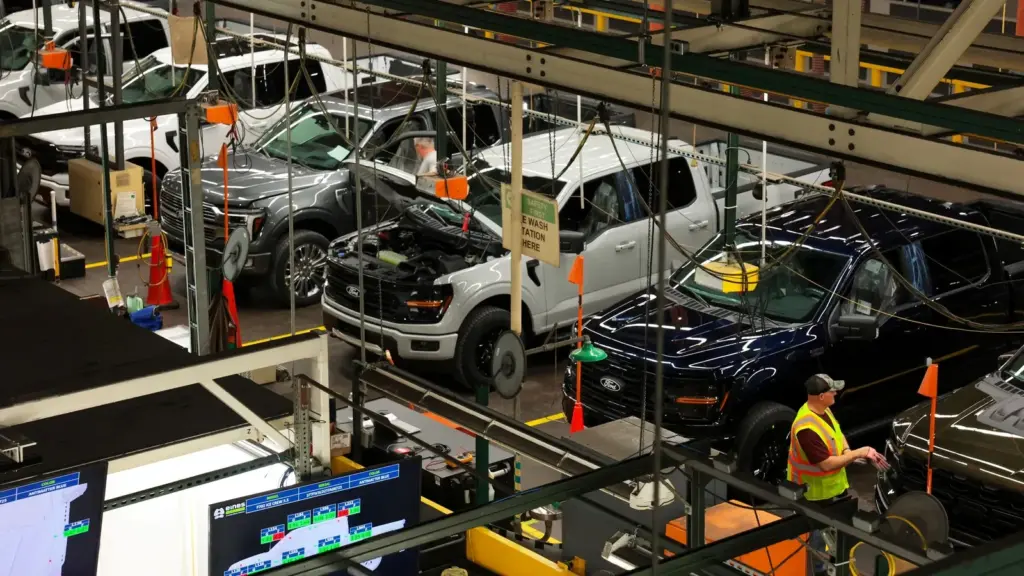
The United States hazardous waste sector is undergoing a profound transformation. Fueled by a massive wave of domestic manufacturing investments, the reshoring of automotive production, unprecedented federal funding for semiconductor fabrication, and a surge in biotech infrastructure dedicated to vaccine development and weight-loss drugs, the industrial landscape of the nation is shifting dramatically. While these economic tailwinds are rejuvenating American industrial might, they are simultaneously generating complex new streams of hazardous and specialty wastes.
Against this backdrop, environmental services giants like Veolia North America are recalibrating their operational strategies. Logistics bottlenecks experienced during the COVID-19 pandemic and the compounding pressures of extreme weather events—such as Winter Storm Uri in 2021—laid bare the fragility of existing supply chains. The volume of material flowing through the national hazardous waste network briefly outpaced the available infrastructure, forcing a rigorous re-examination of how the United States manages its most volatile byproducts.
Although the U.S. Environmental Protection Agency (EPA) maintains that the nation currently possesses adequate permitted disposal capacity to handle projected volumes through at least 2049, the hazardous waste sector faces compounding variables. Long permitting timelines for new facilities, unexpected environmental disasters like the 2023 train derailment in East Palestine, Ohio, and the vulnerabilities of aging Superfund sites to extreme weather events create an unpredictable operational environment. Furthermore, as major manufacturers pivot away from managing their own waste processing operations, the burden is shifting increasingly to specialized commercial providers.
This comprehensive report examines the intersection of industrial growth, environmental regulation, and corporate strategy. By analyzing recent market dynamics, executive insights from industry leaders, and the latest EPA capacity assessments, we explore how the U.S. hazardous waste sector is preparing for a high-demand, technologically evolving future.
Detailed Chronology of Market Shifts and Corporate Adaptations
To fully understand the current state of the hazardous waste landscape, it is necessary to trace the sequence of events and operational stress tests that have guided industry leaders over the past several years.
The Pandemic and Climate Stress Tests (2020–2021)
The structural vulnerabilities of the North American hazardous waste network were sharply exposed during the global health crisis of 2020 and the severe weather disruptions of early 2021. According to Bob Cappadona, CEO of Veolia’s hazardous waste business in North America, the simultaneous surge in certain industrial sectors and the sudden, sweeping disruptions in national logistics caused a dangerous mismatch between waste volumes and the operational capacity required to support them.
During this same window, industrial generators began evaluating the financial and operational viability of maintaining their own in-house waste processing operations. Many corporations concluded that managing specialized incinerators and treatment facilities was no longer part of their core competency. This prompted a wave of strategic asset divestitures:
- 2020: Alcoa made the strategic decision to sell its industrial site in Arkansas, which included waste management assets, to Veolia.
- 2021: Industrial conglomerate 3M elected to close its hazardous waste incinerator in Minnesota, reflecting a broader trend where major corporations stepped back from operating dedicated disposal infrastructure.
The Post-Pandemic Reshoring Boom (2022–2024)
As the economy rebounded, federal legislative actions—most notably the CHIPS and Science Act—catalyzed unprecedented capital deployment into domestic manufacturing. Semiconductor fabrication plants, high-tech automotive factories, and advanced biotechnology facilities began breaking ground across the country.
This industrial renaissance brought an immediate surge in specialized, complex waste streams. Recognizing that a wave of corporate incinerator closures might flood the commercial market all at once, waste management firms closely monitored the situation. However, as Cappadona noted, that synchronized wave of closures did not materialize in the anticipated manner; instead, individual manufacturers began evaluating their waste portfolios on a case-by-case basis.
To stay ahead of mounting demand, Veolia accelerated its capital investments. The company initiated the construction of a massive, 100,000-ton-per-year hazardous waste incinerator at the former Alcoa location in Arkansas. Concurrently, merger and acquisition (M&A) activity across the sector intensified, with key players aggressively positioning themselves to capture regional market share.
Regulatory Milestones and Current Developments (2025 and Beyond)
The release of the EPA’s latest hazardous waste capacity assessment in early 2025 provided a baseline reassurance for the industry, projecting that existing permitted capacity could absorb forecasted volumes for decades. Yet, the report underscored the critical need for proactive planning, waste minimization, and state-level support for new infrastructure development.
Today, Veolia and its industry peers are executing multi-pronged expansion strategies. These include finalizing the groundbreaking Arkansas thermal facility, evaluating potential processing enhancements at major hubs like Port Arthur, Texas, and pursuing targeted acquisitions on both the East and West Coasts to cater to niche manufacturing requirements.
Supporting Context & Metrics: The Numbers Driving the Sector
An objective analysis of the hazardous waste sector requires a close examination of empirical data, facility distribution, and generation metrics.
Generation Metrics by Industry
According to recent industry data, the industrial and commercial sectors generating hazardous waste are heavily concentrated in specific pillars of the American economy:
- Manufacturing: Accounted for a staggering 90% of total U.S. hazardous waste generation in 2023.
- Transportation: Represented the second-largest sector contributing to hazardous waste streams.
- Emerging Sectors: Analysts warn that current baseline estimates for 2033 waste generation could prove conservative if external economic stimulants—such as new steel tariffs, the rapid expansion of artificial intelligence data centers, and advanced biotech manufacturing—accelerate investment further.
Current National Infrastructure Footprint
Data compiled for industry assessments highlights a highly consolidated commercial disposal landscape in the United States:
- Hazardous Waste Landfills: Only 17 commercial hazardous waste landfills operate nationwide. The vast majority of total tonnage is managed by a small oligopoly of operators, including Arcwood Environmental, Clean Harbors, Republic Services, and Veolia. The overall count of active landfills has experienced a steady decline over the past decade.
- Incinerators: There are currently 11 commercial hazardous waste incinerators operating in the U.S. While the total number remains tightly constrained due to stringent permitting requirements, recent project development has been led by active players such as Arcwood, Clean Harbors, and Veolia.
- Energy Recovery Facilities: The network includes 12 operational energy recovery facilities specialized in handling chemical byproducts.
The Regulatory Horizon
Under the Comprehensive Environmental Response, Compensation and Liability Act (CERCLA), states are required to provide assurances of hazardous waste capacity. The EPA’s current hazardous waste assurance framework is legally mandated to expire on December 31, 2029. Consequently, state and federal regulators will be required to execute a comprehensive new capacity assessment leading up to that deadline to ensure the industrial base does not outstrip available environmental infrastructure.
Official Statements and Industry Insights
The strategic evolution of the hazardous waste sector is best understood through the perspectives of industry executives and regulatory authorities who navigate its complexities daily.
Bob Cappadona, CEO of Veolia’s North American Hazardous Waste Business
In discussions surrounding industrial expansion and waste management logistics, Bob Cappadona has emphasized the critical importance of early engagement between waste service providers and industrial clients.
Addressing how modern manufacturers approach their environmental responsibilities, Cappadona pointed to proactive partnerships where corporations engage Veolia before construction has even begun:
"The better decisions that are made at that point of generation have an impact on how that material may be able to be managed post-use of the original generator," Cappadona explained.
Highlighting the success of upfront waste sorting and pollution prevention, he noted that one major semiconductor client achieved a remarkable 99% recycling rate for its waste streams through meticulous initial sorting and on-site management practices. In certain instances, Veolia is exploring hyper-localized models—such as siting operations directly adjacent to a semiconductor manufacturing plant—to drastically reduce transportation emissions and logistical overhead.
Regarding industry-wide capacity fears and facility closures, Cappadona observed:
"I think at times there was an assumption that there was going to be a wave that they [manufacturers] were all going to shut down at the same time. We haven’t seen that. There’s some other facilities that are going through similar evaluations."
Looking toward the future of treatment methodologies, Cappadona advocated for a paradigm shift that looks beyond traditional thermal and burial options:
"Those are traditional treatment methods. What about the untraditional treatment methods? I think that’s really the target for our group—how do we use those legacy older technologies in combination with some of the newer technologies to meet the demands of industry."
EPA Perspectives on Capacity and Compliance
An EPA spokesperson emphasized that while the agency’s 2025 assessment projects sufficient permitted capacity through at least 2049, the regulatory body remains vigilant. The EPA actively encourages comprehensive waste minimization programs across all industrial sectors. Furthermore, the agency has urged individual states to proactively seek pathways for developing new incineration and landfill capacity to safeguard against unexpected regional shocks or accelerated industrial growth.
Future Outlook: Technology, Integration, and Strategic Expansion
As the United States looks toward the horizon of 2030 and beyond, the hazardous waste sector faces a delicate balancing act between supporting aggressive industrial expansion and maintaining stringent environmental safeguards.
The Rise of Advanced Thermal Facilities
The impending completion of Veolia’s 100,000-ton-per-year thermal facility at the former Alcoa site in Arkansas marks a milestone for the domestic sector. Designated as the first H050-qualified thermal facility in the United States, this installation represents the pinnacle of modern destruction and thermal treatment technology. Simultaneously, established operators like Clean Harbors and Arcwood are upgrading existing footprints, while Veolia evaluates potential expansions—such as boosting processing efficiencies at its Port Arthur, Texas, incinerator—to meet surging regional demands.
Embracing Non-Traditional Treatment and Recycling
Industry leaders increasingly recognize that traditional disposal methods—landfilling, incineration, and fuel-blending—must be supplemented by advanced recycling and circular economy technologies. Veolia’s recent strategic investments reflect this transition:
- The establishment of a specialized recycling facility in Arizona tailored specifically to recover materials from semiconductor manufacturing.
- The acquisition of a medical waste and biotech processing site in New England to safely manage specialized healthcare and pharmaceutical waste streams.
By combining legacy thermal and containment infrastructure with cutting-edge chemical recycling, solvent recovery, and on-site wastewater treatment, the hazardous waste sector is transforming from a reactive cleanup mechanism into an integrated partner in sustainable manufacturing.
Conclusion
The convergence of domestic manufacturing reshoring, federal legislative incentives, and heightened environmental awareness has forever altered the U.S. hazardous waste sector. While the EPA’s capacity assessments offer reassurance that national infrastructure can support projected industrial output for decades to come, the operational realities demand constant innovation. Through strategic mergers, state-of-the-art facility construction, and a commitment to upfront waste minimization and advanced recycling, industry leaders are successfully engineering a resilient framework capable of safely managing the byproducts of America’s technological future.