Executive Overview
As the United States hurtles toward a critical midterm election cycle, the White House finds itself ensnared in an escalating economic and political trap of its own making. More than two months have elapsed since the fragile ceasefire between the United States and Iran disintegrated, yet American consumers continue to bleed cash at the local pump. The national average for regular gasoline hovers stubbornly near $4.11 per gallon—representing a staggering surge of more than 90 percent compared to this time last year—while diesel prices remain at punishingly historic highs.
For President Donald Trump, soaring energy costs have transformed from an overseas geopolitical complication into an immediate domestic emergency. With Republican congressional majorities hanging in the balance, the administration has scrambled to enact a multifaceted, high-stakes intervention. Over the past several weeks, the White House has rolled out a sweeping suite of emergency measures: aggressively courting the long-dormant Venezuelan oil reserves, pressuring domestic refiners behind closed doors, and rolling back crucial environmental mandates to artificially inject relief into a choked fuel supply.
Yet, interviews with energy economists, market analysts, and industry insiders reveal a sobering reality: the administration’s emergency playbook may be structurally mismatched to the true villain of the current economic crisis. While policymakers focus heavily on crude oil supply lines and geopolitical choke points, the beating heart of the global fuel price crisis is not a shortage of raw petroleum. Rather, it is a catastrophic, systemic breakdown in global refining capacity.
With critical processing infrastructure crippled by overseas military conflicts, Ukrainian drone strikes on Russian diesel plants, and domestic facilities operating at bone-dry maximum capacities without scheduled maintenance, the math simply does not add up. Even an aggressive pivot toward Latin American heavy crude or sudden environmental waivers cannot instantly solve a bottleneck of this magnitude. As political pressure mounts and the looming threat of the Atlantic hurricane season threatens the Gulf Coast refining hub, the Trump administration faces a race against time—and economic reality—to tame fuel prices before voters head to the polls.
Detailed Chronology: From the Strait of Hormuz to the Oval Office
To understand how the American consumer arrived at $4.11-per-gallon gasoline, one must trace a cascading series of geopolitical shocks and domestic policy maneuvers that have violently reshaped the global energy landscape over the past year.
The Spark: The Iran Conflict and the Blockade
The current crisis traces its lineage to the outbreak of hostilities between the United States and Iran, which culminated in a military standoff and the effective blockade of the critical Strait of Hormuz—the maritime artery through which a massive share of Middle Eastern crude flows to global markets. Although initial fears of an unmitigated global supply apocalypse were partially staved off as international markets found ways to reroute flows and conserve oil, the structural damage inflicted upon energy infrastructure was profound.
Refining facilities throughout the Middle East were forced to scale back operations or shut down entirely amidst the regional volatility. Concurrently, the ongoing conflict in Eastern Europe saw a wave of precision Ukrainian drone strikes systematically target and neutralize critical Russian diesel refineries. Together, these events wiped out millions of barrels per day of global processing capability, setting the stage for a historic crunch.
The Escalation: The Maduro Raid and the Venezuelan Pivot
Recognizing that traditional channels could not supply sufficient raw materials to offset the losses, the Trump administration took unprecedented kinetic action in January. U.S. forces executed a high-profile raid in Venezuela, capturing strongman leader Nicolás Maduro and announcing an ambitious, aggressive federal blueprint to forcibly revive the country’s moribund, state-controlled oil industry.
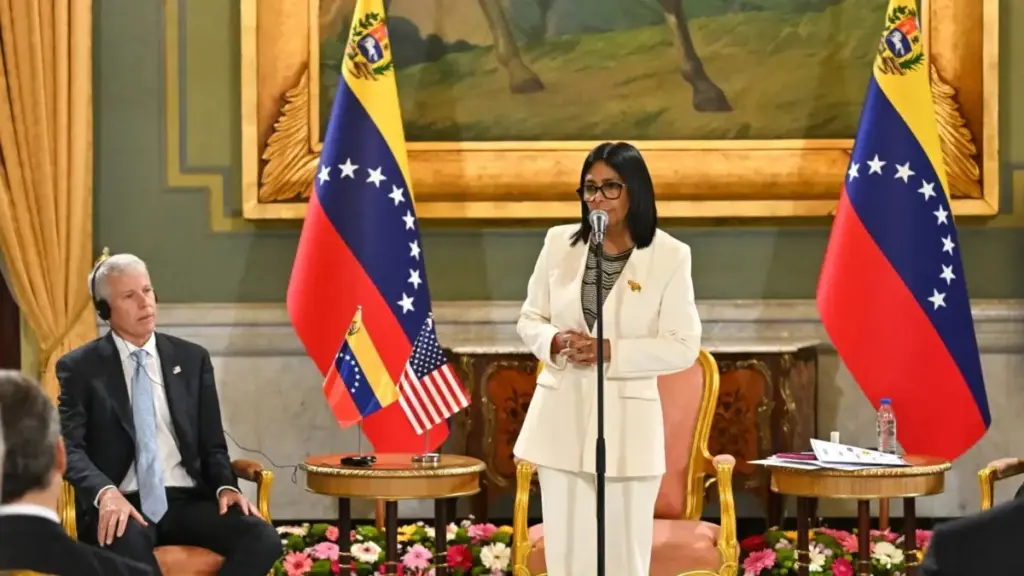
Over the subsequent months, the administration systematically dismantled traditional hurdles to make Venezuelan assets palatable to Western capital. Washington eased crippling economic sanctions and leaned heavily on interim leader Delcy Rodriguez to rewrite the nation’s restrictive oil laws. These diplomatic and economic arm-twisting efforts culminated in a flurry of high-stakes announcements:
- The Pentagon’s Stake: The Department of Defense announced a direct stake in North American Blue Energy Partners, a private Venezuelan enterprise controlling approximately 20 percent of the nation’s vast reserves. This entity aims to aggressively ramp up production in oil fields previously dominated by Chinese and Russian state firms.
- Chevron’s Multi-Billion Dollar Bet: Following direct negotiations at the Miraflores Palace in Caracas, energy giant Chevron formalized an agreement to double its production footprint in Venezuela, committing massive capital to unlock heavy crude reserves.
The White House Summons and Environmental Rollbacks
As the summer months wore on and public frustration reached a boiling point, President Trump’s rhetoric hardened. In a fiery Oval Office briefing last month, the president openly excried the energy sector, declaring, "Based on a shortage, they’re making too much money. They ought to give some of that back to the public, and they better cut the retail price, the consumer price."
This frustration translated into direct executive pressure. Earlier this week, the president summoned top refining executives to the White House for a high-stakes, closed-door summit aimed at coercing the industry into lowering prices at the pump. The meeting concluded under a cloud of opacity: executives departed without offering public statements, and the administration pointedly declined to release an attendee roster.
Concurrently, the Environmental Protection Agency (EPA) deployed regulatory relief levers. The agency announced an early termination of its stringent summer ethanol blending requirements—mandates originally designed to limit urban smog by forcing refiners to integrate biofuels into gasoline. Furthermore, the EPA unleashed a wave of small-refinery waivers, exempting dozens of facilities nationwide from adherence to the Renewable Fuel Standard. While framed as a measure to relieve cost pressures on refiners, the move sparked immediate, fierce blowback from agricultural lobbies and Midwestern lawmakers.
Supporting Context & Metrics: Decoding the "Crack Spread" and Refining Bottlenecks
While everyday motorists fixate on the final dollar figure displayed on gas station marquee signs, industry analysts monitor a far more technical, telling metric: the crack spread.
The Exploding Crack Spread
The crack spread measures the price differential between a barrel of raw crude oil and the refined petroleum products derived from it, such as gasoline and diesel. In recent months, this spread has exploded to an unprecedented historic high of more than $70 per barrel.
For economists and market observers, this figure acts as an unmistakable alarm bell. It signals that the market for refined products—rather than raw crude—has completely detached from historical norms. It is the mathematical proof underlying President Trump’s populist grievances: domestic and international oil companies are extracting extraordinary, windfall profits not merely because crude is expensive, but because the global infrastructure required to convert that crude into usable fuel is severely constrained.
Operating at the Breaking Point
To capitalize on these soaring margins, the largest domestic refineries in the United States have been operating at or near 100 percent maximum capacity for several consecutive weeks—a sustained intensity unseen in recent industrial history. In their relentless pursuit of profit amid high prices, operators have repeatedly deferred mandatory, routine seasonal maintenance.
This hyper-extended operating posture, however, carries a dangerous hidden cost. By bypassing essential upkeep to squeeze out every possible gallon of gasoline, refiners are pushing their heavy industrial machinery to the absolute brink of mechanical failure.
The Heavy Crude Mismatch
Compounding the refining crisis is a fundamental mismatch in chemical engineering. The massive influx of new petroleum anticipated from the administration’s Venezuelan initiatives consists predominantly of heavy, sour crude oil.
Only a specialized subset of American refineries—primarily clustered along the Gulf Coast—possess the sophisticated coking and cracking units required to process heavy crude into high-grade gasoline and diesel. Because these specific facilities are already running flat-out to maximize their profit margins, they possess virtually zero spare bandwidth to ingest and process additional Venezuelan barrels in the near term.
Al Salazar, an expert energy analyst at Enverus Intelligence who has spent decades studying North American heavy oil markets, offered a blunt assessment of the situation:
"Everything that the Venezuelans could produce right now, I’m sure they’re squeezing out. You could get incremental production out of there in six to twelve months, but what really is causing the gasoline and diesel price spike is the lack of refining capacity."
Salazar noted that even under the most optimistic projections, scaling up modern heavy-oil processing infrastructure requires a multi-year development runway. This timeline completely disqualifies the Venezuelan gambit as a viable short-term fix for the current political crisis.
Official Statements and Stakeholder Perspectives
The convergence of aggressive executive action, volatile foreign interventions, and sudden regulatory rollbacks has triggered a chaotic crossfire of public statements from politicians, corporate leaders, and legal experts.
The White House Perspective
The Trump administration maintains an optimistic, if defiant, public posture regarding the ultimate efficacy of its interventions. Speaking from the Oval Office, President Trump expressed total confidence in the administration’s long-term economic trajectory while hedging on immediate electoral relief:
"I think it’s going to have a tremendous impact; ultimately, prices are going to come down. Will it happen before the election? I can’t tell you that."
This sentiment underscores a desperate gamble by administration officials: even if relief arrives too late to ease voter pain at the ballot box in November, aggressive federal action demonstrates proactive leadership in the face of corporate profiteering.
The Venezuelan Legal and Business Calculus
In Caracas, the business community has reacted to the sudden tectonic shift in governance and industrial partnerships with cautious optimism tempered by deep institutional anxiety.
Ramón Andrade, a prominent energy business attorney and partner at the Caracas-based law firm Ponte Andrade & Casanova, characterized the local read on the situation as fundamentally positive regarding sector revival. However, Andrade issued a sharp cautionary note regarding the rushed legal arrangements between the Pentagon and local private entities like North American Blue Energy Partners:
"In general, the read is positive… but on the Pentagon deal, I think we need to look at what’s actually going to be signed."
Legal scholars and constitutional analysts in Venezuela have pointed out that ceding vast national resource wealth to foreign military powers under an unelected interim administration—led by Delcy Rodriguez and featuring figures like Alejandro Betancourt, whose legal entanglements abroad were reportedly mitigated by U.S. intervention—may directly violate the Venezuelan constitution. Because the interim government has yet to face a legitimate national electorate, the longevity and enforceability of these multi-billion-dollar energy pacts remain highly dubious.
The Biofuel and Agricultural Battleground
The EPA’s decision to grant sweeping waivers to refiners and prematurely lift summer ethanol blending mandates has ignited a fierce, multi-front war between Big Oil and the American agricultural sector.
Midwestern lawmakers and powerful biofuel coalitions immediately condemned the administration’s actions, arguing that slashing ethanol demand directly harms American corn farmers who depend heavily on the lucrative biofuel market. Concurrently, traditional industry groups like the American Petroleum Institute expressed reservations, warning that erratic, ad-hoc regulatory waivers create a chaotic and unpredictable operating environment for refineries trying to plan capital expenditures.
Whether these exemptions will successfully lower retail prices remains a subject of intense debate among economists. Critics argue that multi-billion-dollar refining conglomerates like Marathon and Chevron will simply pocket the savings rather than passing price relief down to the consumer at the pump.
Future Outlook: Electoral Risks and Natural Threats
As the calendar inexorably advances toward the midterm elections, the confluence of high fuel prices and compounding environmental vulnerabilities presents an ominous outlook for the incumbent party.
The Midterm Electoral Penalty
Historically, economic pain at the pump serves as an unsparing executioner for the party holding the White House. A comprehensive historical analysis conducted by Politico examining midterm election cycles dating back to 1978 reveals a brutal empirical trend: on average, the president’s political party loses 25 more congressional seats in midterm elections following a significant gasoline price spike compared to cycles where fuel prices trend downward.
With prices sitting roughly $1.50 above pre-conflict baselines across many states, Republican candidates face an uphill battle to insulate themselves from voter anger. The stubborn persistence of these high prices means that even a sudden, miraculous opening of the Strait of Hormuz tomorrow would fail to instantly un-kink the physical bottlenecks plaguing the global refining ecosystem.
The Gathering Storm on the Gulf
Compounding these man-made and geopolitical crises is the relentless threat of nature. Approximately half of the entire refining capacity of the United States is anchored directly along the Gulf of Mexico, placing it squarely in the bullseye of the Atlantic hurricane season.
Although long-range meteorological forecasters initially predicted a relatively tranquil storm season, the inherent volatility of the region leaves zero margin for error. A stark reminder occurred this week as Tropical Depression Edouard materialized in the Gulf, tracking directly over a major Texas refinery complex. While the system ultimately fizzled out into a minor disturbance before achieving catastrophic hurricane status, it served as a terrifying cryptographic warning for energy markets.
A single, high-intensity hurricane making landfall in the heart of the Gulf Coast refining corridor could instantly wipe out millions of barrels of daily processing capacity, sending shockwaves through an already fractured market and driving gasoline prices toward unprecedented, catastrophic heights just as voters cast their ballots.
Ultimately, the great energy crunch of this election cycle has exposed the profound limitations of executive fiat in a globally interconnected, structurally broken commodities market. Neither rushed geopolitical takeouts in South America nor hurried regulatory rollbacks in Washington can bypass the cold, unyielding laws of industrial capacity. Until global refining infrastructure is repaired, expanded, and fully modernized, the American consumer—and the politicians who represent them—will remain trapped at the mercy of the crack spread.