Executive Overview
The United States energy storage market is currently experiencing a period of historic, unprecedented growth. Across the country, massive battery energy storage systems (BESS) are coming online at a breakneck pace, radically shoring up the electrical grid, boosting reliability against extreme weather events, and slashing carbon emissions. By capturing and retaining surplus power generated from intermittent renewable sources such as wind and solar, these batteries are proving to be the linchpin of the clean energy transition.
Yet, this green infrastructure boom is built on a paradox: it relies overwhelmingly on cheap, high-performance Chinese battery technology. For years, policymakers in Washington have viewed this dependence not as a cooperative global triumph, but as an acute strategic vulnerability. The United States has engaged in a multi-pronged, increasingly aggressive effort to decouple its critical energy supply chains from Beijing.
This economic statecraft reached a dramatic apex when the Trump administration issued a sweeping executive order declaring a national emergency. The directive effectively bans Chinese-manufactured batteries from being utilized in American grid-scale energy storage systems.
This move represents a high-stakes gamble. By cutting off access to the world’s most dominant and cost-effective manufacturer of clean energy technology, the U.S. government is attempting to force the rapid development of a domestic manufacturing base. However, this strategic maneuver comes with a staggering price tag. Short-term project delays, soaring capital costs, legal ambiguities surrounding existing grid infrastructure, and the looming threat of project cancellations now threaten to slow the very clean energy transition the policy aims to protect. As the global community watches, the United States has found itself at a profound crossroad: balancing the urgent, existential need for rapid decarbonization against the long-term imperative of technological and economic sovereignty.
Detailed Chronology: Escalating Disconnects in the Battery Supply Chain
The friction between the United States and China over battery supply chains did not materialize overnight. It is the result of a deliberate, multi-year escalation in trade policy, industrial strategy, and national security measures spanning successive presidential administrations.
2022: The Inflation Reduction Act and the Sourcing Mandates
The foundational architecture of America’s current industrial policy was laid back in August 2022 with the passage of the landmark Inflation Reduction Act (IRA). While the legislation injected unprecedented financial capital into clean energy, it also introduced stringent domestic-content and sourcing requirements.
Under the original design of the IRA’s tax credits, clean energy developers faced strict limits on where a battery’s critical minerals could be mined, processed, or recycled. Furthermore, it dictated strict geographic rules regarding where the battery cells and their underlying components were assembled. The intent was clear: use the carrot of federal financial incentives to starve foreign entities of concern—predominantly China—of American market share, thereby encouraging the growth of domestic supply chains and allied manufacturing networks.
January 2025: The Tariff Hike
As regulatory frameworks evolved, fiscal penalties on imported technology grew heavier. In January 2025, the U.S. government dramatically escalated trade pressure by hiking import taxes on foreign-made batteries from 7.5% to a punishing 25% under Section 301 tariffs. This move was designed to artificially elevate the cost of Chinese imports, narrowing the steep price gap that had long made foreign alternatives overwhelmingly attractive to private developers.
Late August 2025: The National Emergency Executive Order
Despite tariffs and tax credit restrictions, Chinese-manufactured batteries continued to anchor a vast share of U.S. energy storage projects due to their unmatched affordability and reliability. Recognizing this persistent reliance, the Trump administration took a far more drastic step in late August 2025.
Citing national security threats to the nation’s electrical grid, the White House issued an executive order declaring a formal national emergency. This decree prohibited the installation of "any foreign-produced bulk-power system electric equipment" deemed to pose a security risk. The order specifically targeted battery energy storage systems, along with associated critical components like inverters and transformers. Unlike previous tariff mechanisms or tax credit exclusions, this was an outright regulatory prohibition, sending immediate shockwaves through the energy sector.
2026 and Beyond: The New Tax Credit Thresholds
Complementing the executive order, new legislative measures slated to take effect in 2026 establish even tighter constraints. Moving forward, 55% of the total cost of materials used in new energy storage projects must originate from outside China and other restricted nations if the developers hope to qualify for federal tax credits. Failure to meet this threshold effectively strips projects of financial viability, rendering domestic or allied sourcing an absolute mandate for survival.
Supporting Context & Metrics: The Scale of Reliance and Economic Realities
To understand why the U.S. government felt compelled to take such aggressive action, one must examine the staggering dominance of China in the global clean energy ecosystem. Years of state-backed financial support, deep integration into raw material extraction, and unmatched refinement experience have allowed China to build an unassailable lead in technologies like solar panels and advanced battery cells.
The Cost and Scale Disparity
The economic reality facing American energy developers is stark. Today, batteries produced domestically within the United States are significantly more expensive than their Chinese counterparts. Even if developers pivot away from China to alternative international suppliers—such as South Korea or Japan—the resulting components command a substantially higher price tag.
According to market analysts, this price differential is not trivial; it can dictate whether a utility-scale renewable project breaks even or operates at a profound loss. When cheap Chinese imports are abruptly removed from the equation, the overall capital expenditure required to build out the U.S. power grid spikes dramatically.
Near-Term Market Disruptions and Bottlenecks
The immediate aftermath of the August 2025 executive order has plunged the domestic energy storage market into a state of acute uncertainty. Analysts at BloombergNEF note that project deployments are likely to slow significantly in the near term. Developers are currently pausing construction pipelines while they wait for definitive regulatory guidance from the Department of Energy, which is expected to clarify the exact compliance parameters by the end of the year.
This regulatory limbo introduces severe operational risks:
- Alternative Sourcing Scramble: Projects caught mid-pipeline must now scramble to identify non-restricted cell suppliers. Securing these alternative streams takes time and invariably inflates project budgets.
- The Threat of Cancellations: In a worst-case scenario, Isshu Kikuma, an energy storage analyst at BloombergNEF, warns that some financially marginal projects could face outright cancellation if alternative supply chain arrangements prove too costly or time-consuming to execute.
- The Retroactive Dilemma: Technically, the language of the executive order applies broadly, even casting a shadow over existing energy storage plants already tied into the grid. However, industry experts view full retroactive enforcement as an administrative impossibility. Because the vast majority of operational utility-scale storage facilities currently utilize Chinese-supplied batteries, enforcing the order to the letter would mean physically removing or disconnecting most of the installed battery energy storage capacity currently keeping the U.S. grid stable. Such a move would trigger unprecedented blackouts and reliability crises, making it an unviable path forward.
The 2030 Horizon: Domestic Manufacturing Capacity
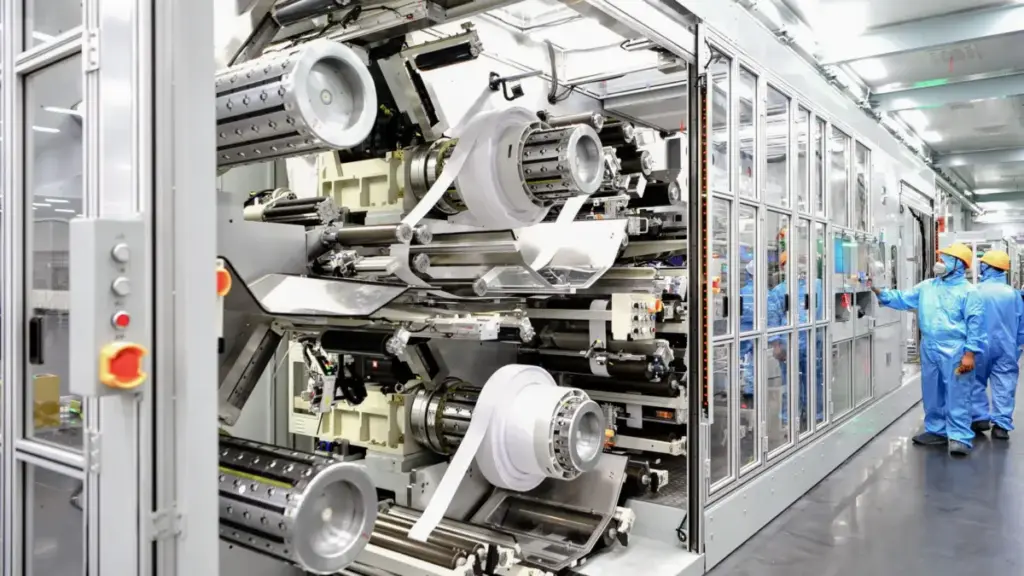
Proponents of the ban argue that short-term pain is a necessary prerequisite for long-term strategic independence. Current industrial projections suggest that the United States will eventually possess the domestic manufacturing capacity to meet its own surging demand for energy storage batteries.
Optimistic forecasts indicate that sufficient domestic production capacity could theoretically come online by roughly 2030. However, industry analysts caution that factory ramp-up phases are notoriously fraught with delays. Actual output matching full domestic demand may not materialize until well into the 2030s.
Interestingly, an ironic twist in the broader automotive market is currently aiding this industrial pivot. A temporary slowdown in the electric vehicle (EV) market has left several major battery manufacturing facilities with excess capacity. Automakers and suppliers—including companies like LG Energy Solutions, Samsung SDI, Ford, and SK On—are actively retooling factories originally designed for EV batteries to produce cells specifically tailored for grid-scale energy storage instead.
Official Statements and Industry Perspectives
The sudden and sweeping nature of the administration’s actions has elicited a complex array of reactions from industry analysts, market participants, and trade associations. While national security officials frame the measures as an indispensable shield against foreign espionage and infrastructure disruption, commercial leaders are sounding alarms over operational stability.
Shan Tomouk, the energy storage and energy lead for industry analyst firm Benchmark Mineral Intelligence, captured the prevailing industry sentiment following the August executive order:
"An outright ban was a bit of a surprise, and it does create a bit of concern for domestic players in the US."
Tomouk’s assessment highlights the precarious position of commercial developers who have spent years optimizing their supply chains around globalized, cost-effective manufacturing hubs.
From the perspective of BloombergNEF researchers, the primary danger lies in the velocity of the transition versus the readiness of domestic supply chains. Isshu Kikuma emphasized the precarious mechanics of compliance:
"Depending on the detailed guidance from the Department of Energy… some projects may need to find alternative sources for their cells, whether they’re domestically produced or imported from other countries. These will likely be more expensive than Chinese imports. Worst case, those projects could get canceled."
Conversely, defenders of the policy argue that allowing a geopolitical adversary to maintain an effective monopoly over the critical infrastructure underpinning the American power grid represents an unacceptable existential risk. From this viewpoint, reliance on foreign hardware creates a silent vulnerability—leaving the bulk-power system susceptible to remote interference, supply cutoffs, or economic coercion during times of international crisis.
Future Outlook: The Global Dilemma of Clean Energy Sovereignty
As the United States navigates the turbulent waters of supply chain decoupling, the implications extend far beyond American borders. The core dilemma facing Washington is a microcosm of a global challenge: How much should sovereign nations leverage cheap, readily available foreign technology to accelerate climate action, versus cutting off major industrial suppliers to force the development of domestic manufacturing capabilities, even when doing so comes at a profoundly higher economic cost?
The Balancing Act
The tension exposes the fragile political and economic balance that governments worldwide must maintain. On one hand, the climate crisis demands immediate, aggressive decarbonization. Every month of delay in deploying renewable energy and storage infrastructure pushes global carbon reduction goals further out of reach and keeps energy costs artificially elevated for consumers. Cheap Chinese technology has historically been the most effective tool available to drive down the cost of the green transition.
On the other hand, transitioning the world’s energy infrastructure from fossil fuels to renewables simply to trade one form of dependency for another—moving from oil cartels to a monopoly over critical mineral processing and battery manufacturing—is viewed by many security strategists as a geopolitical trap.
The Road Ahead for the U.S. Grid
Over the next decade, the success or failure of the U.S. strategy will hinge on execution. If the Department of Energy’s forthcoming guidelines provide enough regulatory flexibility to prevent widespread project cancellations, and if domestic manufacturing facilities can successfully ramp up production without crippling cost overruns, the gamble may pay off. The United States could emerge with a secure, resilient, domestically anchored clean energy economy.
However, if supply bottlenecks persist, if domestic manufacturing fails to scale on schedule, and if project costs spiral out of control, the policy risks choking the very infrastructure it seeks to protect. The coming years will test whether industrial policy can successfully bend the arc of global manufacturing, or if the sheer velocity of the climate crisis will punish nations that attempt to decouple from the world’s reigning energy powerhouse too quickly.