Executive Overview
The United States energy storage market is currently breaking historical records, driven by an urgent mandate to modernize and shore up an aging national power grid. As the integration of intermittent renewable energy sources—such as wind and solar—accelerates, grid-scale batteries have emerged as an indispensable technology. These energy storage systems (BESS) stabilize fluctuations, prevent blackouts, and store excess clean energy for deployment during peak demand hours. By smoothing out the variability of renewables, the storage boom is proving to be a cornerstone of federal efforts to reduce carbon emissions and build a more reliable, resilient electrical infrastructure.
However, this critical clean energy expansion rests upon a geopolitical fault line. For years, the rapid deployment of U.S. energy storage has relied heavily on affordable, high-quality, and readily available Chinese-manufactured batteries. China has established a commanding global lead in the supply chain for batteries, solar panels, and critical minerals through decades of strategic state-backed investments, massive manufacturing scale, and extensive research and development.
Recognizing the systemic vulnerabilities of depending on a geopolitical competitor for critical national infrastructure, Washington has steadily ramped up defensive measures. The conflict has escalated from tax credit exclusions and protective tariffs to a dramatic executive order declaring a national emergency and effectively banning Chinese batteries from the U.S. bulk-power grid.
This policy clash forces a profound, multi-billion-dollar dilemma upon policymakers, energy developers, and consumers alike: To what extent should nations capitalize on cheap, readily available foreign technology to accelerate climate action, versus cutting off dominant supply sources to force the development of domestic manufacturing capabilities—even if doing so incurs steep financial penalties, near-term project delays, and long-term inflationary pressures on the energy transition?
Detailed Chronology of U.S. Decoupling and Policy Escalation
The friction between the rapid imperative to decarbonize and the strategic necessity to onshore clean tech manufacturing has evolved across successive presidential administrations and legislative milestones. Understanding how the United States arrived at an outright ban requires tracing the policy trajectory over the past half-decade.
2022: The Inflation Reduction Act and Supply Chain Guardrails
The foundational legislative turning point occurred in August 2022 with the passage of the landmark Inflation Reduction Act (IRA). While the IRA unleashed unprecedented financial incentives for renewable energy and storage, it simultaneously embedded rigorous domestic content and foreign entity restrictions into the tax code.
The legislation restructured clean energy tax credits to penalize supply chains entangled with adversarial nations. To qualify for lucrative federal subsidies, energy developers had to ensure that specified percentages of a battery’s critical minerals were mined, processed, or recycled domestically or within nations holding free-trade agreements with the U.S. Simultaneously, strict rules dictated where the final battery cells and structural components were assembled, effectively drawing a regulatory line in the sand against unvetted Chinese imports.
2024–January 2025: Tariff Walls and the Section 301 Escalation
As regulatory frameworks matured, the economic pressure on Chinese imports intensified through fiscal policy. Following comprehensive reviews of trade practices under Section 301 of the Trade Act of 1974, the federal government moved to aggressively protect domestic industries.
In January, import tariffs levied on foreign-made batteries—particularly those originating in China—jumped dramatically from a baseline of 7.5% to a punishing 25%. This quadruple increase was designed to artificially close the price gap between inexpensive Asian imports and nascent American-made alternatives, making domestic procurement more financially viable for project developers.
By early 2025, updated regulatory guidance further refined the IRA tax credit parameters, ratcheting up domestic content thresholds and closing loopholes that developers had previously exploited to access subsidies while utilizing Chinese-made cells.
Late August 2025: The National Emergency Declaration and Grid Ban
Despite tariffs and tax penalties, Chinese batteries continued to capture significant market share due to their unmatched cost efficiency and reliability. Frustrated by the slow pace of supply chain decoupling, the Trump administration executed its most dramatic policy intervention yet.
In late August 2025, the White House issued an executive order declaring a national emergency explicitly designed to secure the United States bulk-power system. Invoking national security vulnerabilities related to cyber espionage, remote shutoff capabilities, and critical infrastructure dependencies, the order banned the installation of "any foreign-produced bulk-power system electric equipment" originating from restricted nations.
While the order broadly targeted hardware vulnerabilities, it specifically named battery energy storage systems, along with high-voltage inverters and grid transformers. The sweeping decree caught the energy sector off guard, instantly transforming the debate from a matter of economic protectionism to a matter of acute national defense.
Supporting Context & Market Metrics: The Anatomy of a Vulnerability
To understand the severity of the new executive order, one must examine the baseline metrics governing the global and domestic energy storage markets.
The Economic Disparity
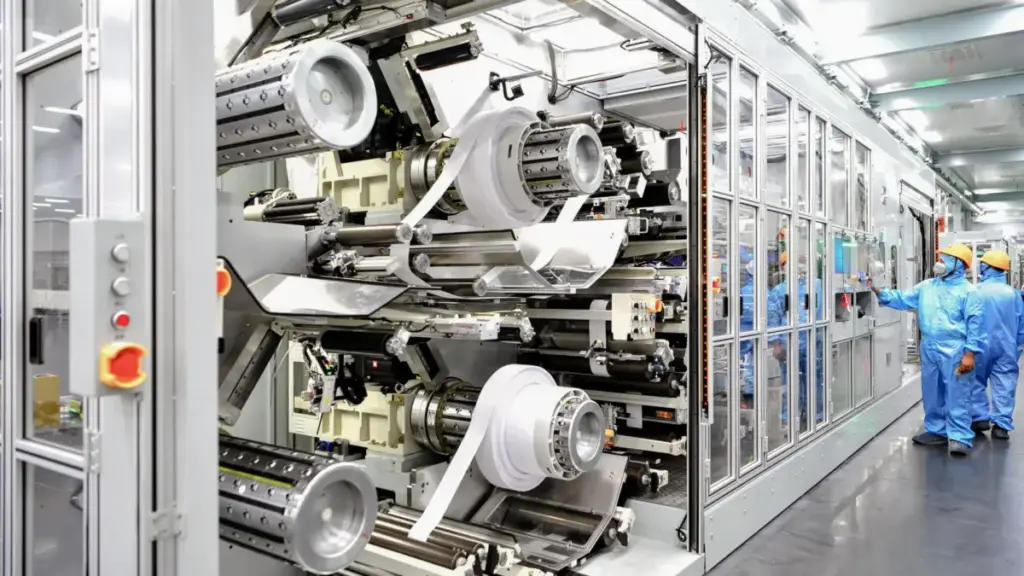
The cost differential between Chinese-manufactured batteries and Western alternatives remains staggering. Decades of industrial clustering, government subsidies, and supply chain vertical integration in China have yielded a manufacturing ecosystem that produces lithium-ion cells at a fraction of the cost seen in the United States or Europe.
Even when developers attempt to pivot away from China to alternative international suppliers—such as South Korea or Japan—the resulting import prices are significantly higher than Chinese equivalents. Domestically produced U.S. batteries carry an even steeper price premium, driven by higher labor costs, nascent manufacturing supply chains, stringent environmental regulations, and capital expenditures required to build gigafactories from scratch.
The Near-Term Disruption
The sudden implementation of the August 2025 executive order has triggered immediate anxieties across the energy sector. According to market analyses by BloombergNEF, the blanket ban threatens to stall the momentum of the U.S. energy storage boom.
Energy developers are currently scrambling to interpret the vague parameters of the order while awaiting detailed compliance guidance from the Department of Energy (DOE), anticipated by the end of the year. During this regulatory limbo, utility-scale projects face severe bottlenecks. Financing has frozen for developments reliant on unvetted supply chains, and project developers are forced to re-evaluate their procurement strategies entirely.
According to Isshu Kikuma, an energy storage analyst at BloombergNEF, the worst-case scenario involves widespread project cancellations. "Depending on the detailed guidance from the Department of Energy, some projects may need to find alternative sources for their cells, whether they’re domestically produced or imported from other countries. These will likely be more expensive than Chinese imports. Worst case, those projects could get canceled," Kikuma warns.
The Paradox of Existing Infrastructure
One of the most legally and logistically complex elements of the new executive order is its technical applicability to existing energy storage plants already operating on the U.S. power grid.
Because the exponential growth of the U.S. storage market over the past five years was overwhelmingly fueled by affordable Chinese battery modules, a strict, literal enforcement of the executive order would require the unprecedented dismantling of the majority of installed storage capacity currently keeping the grid stable. Industry experts note that while enforcing the ban retroactively is technically possible under the wording of the emergency declaration, doing so would destabilize regional grids overnight. Consequently, analysts anticipate the government will grandfather in existing facilities while aggressively policing new installations, though the legal ambiguity continues to unnerve asset owners.
Official Statements and Industry Perspectives
The abrupt shift in federal policy has elicited a spectrum of reactions from market analysts, legal experts, and energy industry executives caught in the crossfire of geopolitical strategy and commercial viability.
Shan Tomouk, energy storage and energy lead for Benchmark Mineral Intelligence, highlights the shockwaves sent through the private sector by the August executive order:
"An outright ban was a bit of a surprise, and it does create a bit of concern for domestic players in the US."
Tomouk’s assessment underscores the delicate balancing act facing American clean energy companies. While domestic cell manufacturers welcome protectionist tailwinds that shield them from cheap foreign competition, system integrators and utility companies who rely on predictable, low-cost hardware now face escalating capital expenditures that could trickle down to rate-paying consumers.
Conversely, national security hawks and administration officials defend the emergency declaration as a long-overdue reckoning. Proponents of the ban argue that allowing an adversarial nation deep access to the software, inverters, and massive energy storage hubs that dictate regional power flows represents an unacceptable strategic risk. In an era where critical infrastructure is increasingly vulnerable to sophisticated cyberattacks and remote interference, the argument goes, energy independence must supersede short-term economic efficiency.
Future Outlook: The Road to 2030 and Beyond
Looking past the immediate turbulence and regulatory uncertainty, the long-term trajectory of the U.S. energy storage market points toward ultimate self-sufficiency—albeit on a delayed timeline and at a higher aggregate cost.
The Domestic Gigafactory Boom
Market projections indicate that the United States possesses a robust pipeline of domestic manufacturing capacity that could theoretically meet national demand by roughly 2030. A wave of new gigafactories backed by major players—including LG Energy Solutions, Samsung SDI, Ford, and SK On—are slated to come online or significantly ramp up production over the next two years.
In an ironic twist of market dynamics, the ongoing slowdown in the consumer electric vehicle (EV) market has provided an unexpected windfall for the stationary storage sector. As automakers experience softer-than-expected demand for passenger EVs, several manufacturing facilities originally designed to build automotive battery cells are currently retooling their lines to produce prismatic and LFP (lithium iron phosphate) cells configured specifically for grid-scale energy storage.
The Timeline to True Independence
Despite the influx of new factory announcements, industry analysts caution against overly optimistic timelines. While nominal nameplate capacity could theoretically satisfy domestic demand by the end of the decade, operational realities—such as workforce shortages, supply chain bottlenecks for precursor materials, and slow factory ramp-up curves—mean that fully independent domestic supply may not genuinely meet aggregate market demand until well into the 2030s.
During the intervening years, developers will navigate an expensive transition period. Projects forced to bypass Chinese supply chains will absorb higher component costs, which will inevitably translate into higher capital costs for grid operators and, ultimately, elevated electricity prices for commercial and residential ratepayers.
A Global Dilemma
Ultimately, the U.S. struggle over battery supply chains serves as a bellwether for a broader global dilemma. As nations worldwide grapple with the imperatives of the green transition, they face a tense political balancing act:
- On one hand, harnessing cheap, highly developed foreign technology is the most mathematically efficient path to slashing carbon emissions, stabilizing power grids, and keeping consumer energy costs manageable in the face of climate change.
- On the other hand, ceding control of foundational green technologies to a single dominant geopolitical rival introduces profound structural vulnerabilities.
How the United States navigates this crossroads over the next five years will not only determine the reliability and cost of its domestic power grid, but will also establish a powerful precedent for how other Western economies manage the friction between national security, industrial policy, and the global fight against climate change.