

Executive Overview
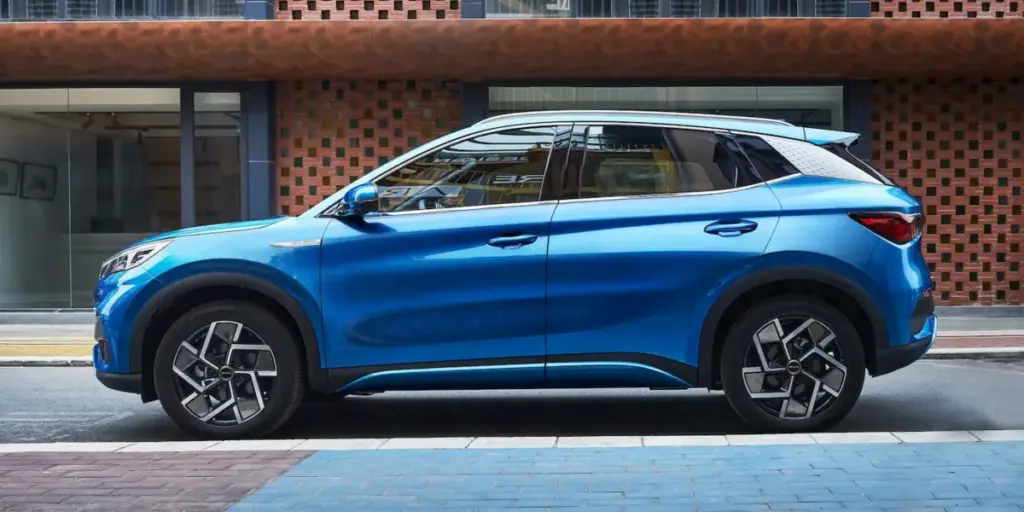
The global electric vehicle (EV) market has officially shaken off a sluggish and uncertain start to 2026, rebounding with striking momentum in the second quarter. Fresh data released by the International Energy Agency (IEA) reveals that worldwide sales of battery-electric vehicles (BEVs) and plug-in hybrids (PHEVs) jumped an impressive 35% in Q2 compared to the first three months of the year. This surge established brand-new quarterly sales records in no fewer than 50 countries, signaling that the electrification of transport is broadening its geographic footprint even as traditional internal combustion engine (ICE) markets stumble.
While the broader global automotive industry faces persistent economic headwinds—including high interest rates, inflationary pressures, and shifting regional regulations—the EV sector continues to decouple from overall car market trends. According to the IEA, global car sales fell by approximately 5% year-over-year during the first half of 2026. Dragged down by tightening economic conditions, fluctuating fuel prices, and sudden policy reversals in key territories like China and the United States, traditional auto manufacturers have experienced suppressed demand.
Yet, outside of these two dominant superpowers, buyers worldwide are plugging in at unprecedented rates. Driven by aggressive export strategies from Chinese manufacturers, robust localized policy support in Europe and Southeast Asia, and a growing consumer desire to escape volatile fossil fuel markets, the IEA has upgraded its full-year forecast. EVs are now projected to account for 29% of all new car sales globally in 2026—a notable upward revision from the agency’s Global EV Outlook published just months prior in May.
Detailed Chronology of the 2026 Automotive Landscape
To understand the current state of the global EV market, it is necessary to examine how the first half of 2026 unfolded across distinct phases of economic friction, geopolitical turbulence, and localized policy shifts.
Q1 2026: A Rocky Beginning and Policy Shockwaves
The year began on precarious footing. In the opening months of 2026, global EV sales actually contracted—a phenomenon largely driven by severe market corrections in China and the United States.
In the United States, the automotive landscape was fundamentally reshaped by regulatory and fiscal policy changes enacted the previous year. Following the official termination of federal EV tax credits by the administration in September 2025, alongside a significant loosening of federal fuel-economy standards, the primary financial catalysts for American EV adoption were abruptly stripped away. Without federal incentives to bridge the upfront cost gap between ICE vehicles and EVs, domestic demand plummeted, leaving American legacy automakers scrambling to retool production lines and scale back aggressive electrification targets.
Concurrently, China—historically the unstoppable engine of global EV growth—experienced a sharp domestic cooling-off period. Driven by saturation in Tier-1 cities, shifting consumer credit availability, and a broader macro-economic slowdown, the world’s largest automotive market hit a temporary plateau, causing global ripple effects in Q1 production figures.
March to June 2026: The Global Pivot and Q2 Resurgence
Despite the stagnation in the world’s two largest EV markets, a profound geographic shift occurred heading into March. Consumers across more than 90 countries recorded definitive year-over-year sales growth during the first half of 2026.
By the time Q2 drew to a close in June, markets such as Australia, Brazil, India, South Korea, and Vietnam emerged as surprising powerhouses. In these regions, EV sales between March and June roughly doubled compared to the exact same period in 2025. This decentralized boom proved that global demand was no longer reliant solely on Beijing or Washington, but was rapidly taking root across emerging economies and secondary industrial markets.
Furthermore, renewed geopolitical instability in the Middle East and the resulting volatility in global oil markets served as an unexpected catalyst. As fossil fuel prices fluctuated wildly, driving up the cost of traditional transport, energy security and cost-predictability pushed consumers in oil-importing nations to accelerate their transition toward locally generated electricity.
Supporting Context & Metrics: Surging Inventories and Shifting Geographies
A deeper dive into the IEA data reveals structural changes in how electric vehicles are manufactured, distributed, and consumed globally.
The Chinese Export Wave and the 1-Million-Vehicle Surplus
While domestic EV sales in China are expected to stagnate year-over-year for the first time this decade—a milestone largely attributed to the maturity of its local market—Chinese manufacturing output has reached staggering new heights. During the first six months of 2026 alone, Chinese factories exported nearly as many electric vehicles as they did across the entirety of 2025.
However, absorption rates have not kept pace with outbound shipping volumes. The IEA estimates that only about two-thirds of these exported EVs have found retail buyers. When combined with unsold inventories from prior shipping cycles, more than 1 million Chinese-made electric cars currently sit in ports, distribution hubs, and storage yards around the globe, actively looking for buyers.
This unprecedented surplus carries profound implications for the global automotive ecosystem:
- Downward Price Pressure: The abundance of affordable, technologically advanced Chinese EVs is intensifying price competition worldwide.
- Penetration of Emerging Markets: These excess inventories are flowing heavily into developing regions in Latin America, Southeast Asia, and parts of Europe where price-sensitive consumers have previously been priced out of Western EV offerings.
- Pressure on Legacy Automakers: Established Western and Japanese automakers, struggling to match the manufacturing efficiencies and cost structures of brands like BYD and Geely, face mounting pressure to compress margins or accelerate their own low-cost EV development programs.
Key Market Metrics at a Mid-Year Glance
- Global EV Sales Growth (Q2 vs. Q1): +35% increase.
- Record-Breaking Reach: 50 countries set all-time quarterly EV sales records in Q2 2026.
- Broad Geographic Adoption: Over 90 countries registered year-over-year EV growth in H1 2026.
- Global Car Market Trend: Overall car sales fell by approximately 5% year-over-year in H1 2026.
- Projected 2026 EV Market Share: Revised upward to 29% of all global car sales.
- China’s Domestic Penetration: Over 60% of all new cars sold in China in 2026 are expected to be electric.
Official Statements and Industry Perspectives
The release of the IEA’s updated mid-year analysis has triggered widespread commentary from energy analysts, trade economists, and industry leaders regarding the bifurcated nature of the modern automotive transition.
Energy analysts point out that the global transition is no longer a linear progression dictated by wealthy Western nations, but rather a multi-polar race heavily influenced by supply chain mastery and industrial policy.
"Road vehicles consume nearly half of the world’s oil, leaving drivers and national economies dangerously exposed to price spikes and supply disruptions," note energy policy researchers tracking the fallout from Middle East energy bottlenecks. "Countries that fail to shield their citizens from fossil fuel volatility through robust electrification policies are finding themselves economically disadvantaged."
Industry trade groups have similarly highlighted the divergence in governmental approaches. While European regulators maintain steady emissions targets and supportive charging-infrastructure frameworks—bolstered by the rollout of advanced "Charging 2.0" networks—the abrupt U.S. policy reversal has drawn sharp criticism from domestic clean-transport advocates. By letting federal tax incentives lapse and rolling back fuel-economy mandates, the U.S. federal government has engineered a localized contraction, ceding technological leadership and manufacturing dominance to foreign competitors who continue to aggressively subsidize and scale next-generation green tech.

Future Outlook: The Next Decade of Mobility
Looking toward the remainder of 2026 and into the next decade, the trajectory of the global automotive industry will be defined by how automakers navigate emerging markets and shifting geopolitical alliances.
China and other emerging economies are projected to account for approximately 60% of total global car demand over the next ten years. Consequently, the automotive brands and nations that successfully capture these developing markets—by offering reliable, affordable, and technologically advanced electric vehicles—will dictate the future leadership of the global auto industry.
For established legacy manufacturers, survival will depend on swift strategic pivots. Companies must address the massive inventory overhang of affordable alternatives by streamlining production, localizing battery supply chains, and embracing software-defined vehicle architectures.
Ultimately, the events of the first half of 2026 have proven that the electrification of transport is irreversible. Even when confronted with domestic policy headwinds in major economies like the United States or temporary plateaus in mature markets like China, global demand continues to find new avenues for expansion. As energy security concerns mount and charging infrastructure matures into its next generational phase, the world moves steadily toward a reality where nearly a third of all new cars sold globally are electric—with that share climbing rapidly toward total market dominance.



