Executive Overview
The global packaging industry is hurtling toward a critical regulatory and operational precipice. For decades, film and flexible packaging—the ubiquitous plastic bags, shrink wrap, multi-layer pouches, and shipping mailers that modern commerce relies on—have represented the recycling sector’s most intractable dilemma. Lightweight, highly versatile, and notoriously difficult to process, flexible plastics have long bypassed the traditional municipal recycling stream.
Today, however, the luxury of ignoring this packaging subset has evaporated. A wave of aggressive Extended Producer Responsibility (EPR) legislation sweeping North America—led most notably by California and Oregon—is radically transforming the compliance landscape. These regulatory frameworks carry severe enforcement mechanisms, threatening to restrict producers from selling products within packaging that fails to meet stringent recyclability and post-consumer recycled (PCR) content thresholds.
Against this backdrop, a comprehensive new collaborative report published by sustainability consultancies Eunomia and Delterra sheds much-needed light on the path forward. The findings make one reality painfully clear: while well-designed EPR programs will undoubtedly drive dramatic increases in the household collection of flexible plastics, collection alone is a hollow victory. Without robust, sustained end-market demand to absorb hundreds of thousands of tons of recovered material, the entire recycling architecture will collapse under its own weight.
Addressing this challenge requires a coordinated, multi-industry crusade. Organizations like The Recycling Partnership (TRP) and its Film & Flexibles Recycling Coalition, alongside specialized initiatives like CalFFlex, are actively working to bridge the gap between municipal collection bins and nascent mechanical processors. Yet, bridging this chasm demands that manufacturers abandon a "wait-and-see" compliance strategy. Companies must proactively integrate recycled flexible plastics into pilot programs, adapt to technical hurdles, and re-engineer supply chains to survive an increasingly unforgiving regulatory future.
Detailed Chronology: The Evolution of the Film and Flex Crisis
To understand how the industry arrived at this critical juncture, it is necessary to examine the historical trajectory of flexible packaging and the compounding pressures that have turned a systemic inefficiency into an urgent crisis.
The Rise of Flexible Packaging and the MRF Dilemma
Over the past thirty years, flexible plastics revolutionized retail and logistics. Offering a remarkably high product-to-package ratio, film and flexible packaging (FFP) drastically reduced shipping weights, lowered transportation fuel consumption, and extended the shelf life of perishable goods. However, this lightweight design proved to be the Achilles’ heel of municipal recycling infrastructure.
Traditional Materials Recovery Facilities (MRFs) were engineered decades ago to sort rigid containers—aluminum cans, glass bottles, and rigid plastic jugs (PET and HDPE). When loose plastic film, bags, and flexible wraps enter these high-speed mechanical sorting facilities, they wreak havoc. Flexible plastics easily billow, wrap around rotating shafts, jam optical sorters, and contaminate clean paper bales. Consequently, the vast majority of MRFs explicitly banned consumers from placing film in curbside bins, relegating the material to localized retail drop-off boxes (such as those outside grocery stores) or sending it straight to landfills.
The Infrastructure Gap Widens
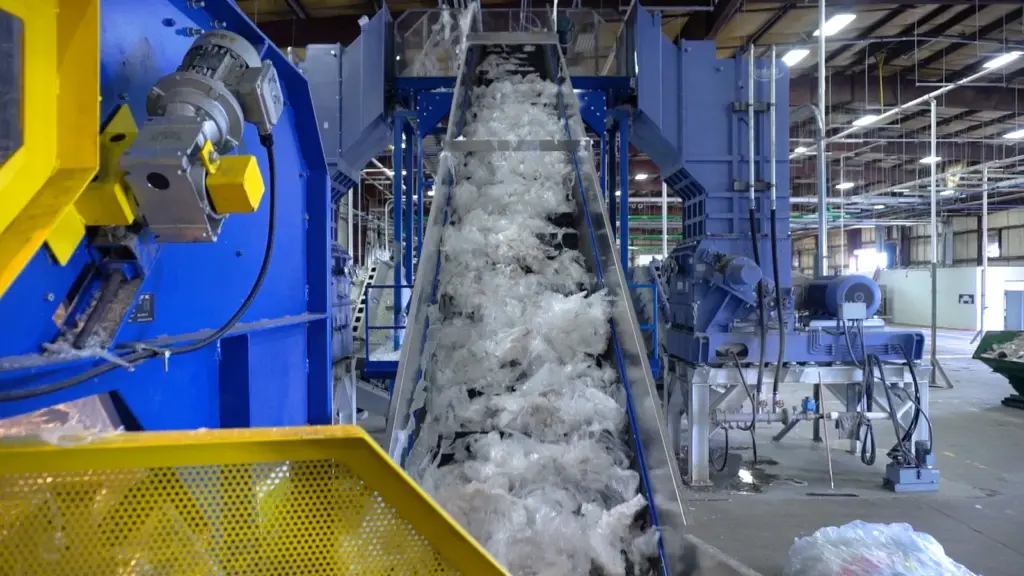
For years, this out-of-sight, out-of-mind approach persisted because the market lacked both collection volume and economic justification. Processing post-consumer film is notoriously difficult. Unlike homogeneous rigid bottles, flexible packaging often consists of mixed polymers (such as low-density polyethylene [LDPE] combined with linear low-density polyethylene [LLDPE] and sometimes polypropylene [PP]), varying colors, and heavy contamination from food residues, paper labels, and aggressive adhesives.
As a result, while industrial and commercial sectors developed relatively robust systems for recycling stretch film from warehouses and distribution centers, household flexible packaging remained largely unrecovered. Estimates from industry groups like The Recycling Partnership indicate that a staggering 98% of U.S. households currently lack access to curbside recycling programs capable of handling film and flex.
The Catalyst: The EPR Legislative Wave
The status quo was permanently disrupted when lawmakers began introducing mandatory producer accountability laws. Recognizing that voluntary corporate sustainability goals were moving too slowly to curb plastic pollution, state legislatures stepped in with legal mandates.
California’s landmark EPR legislation, for instance, establishes an aggressive enforcement timeline, demanding a 65% recycling rate for all single-use plastics by 2032. Given that current recycling rates for flexible plastics languish below 5% nationwide, producers face an astronomical deficit. Similarly, Oregon has instituted a progressive framework requiring a 25% collection target for polyethylene (PE) film by 2028, scaling sharply upward to 50% by the year 2040.
Faced with the prospect of being legally barred from selling their goods in non-compliant packaging, consumer packaged goods (CPG) companies and brand owners have been forced to pivot, sparking an unprecedented rush to build a viable circular economy for film and flex.
Supporting Context & Metrics: Decoding the Eunomia & Delterra Report
The new report from Eunomia and Delterra provides a vital analytical roadmap for navigating this crisis. By moving beyond general sustainability rhetoric, the authors conducted a rigorous technical and economic assessment to determine precisely where and how recovered household flexible plastics can find viable end markets.
The Myth of Price Parity
A central revelation of the report challenges a foundational assumption held by many policymakers: that simply achieving price parity between post-consumer recycled (PCR) resin and virgin plastic resin will naturally drive demand.
Drawing lessons from European markets—where EPR and packaging taxes are more mature—the Eunomia report asserts that virgin-to-PCR price parity is insufficient on its own. Virgin plastic prices fluctuate wildly based on fossil fuel markets, and recycled resins carry inherent processing challenges and sorting costs. Therefore, Producer Responsibility Organizations (PROs) must actively deploy subsidies, financial incentives, and regulatory mandates to make using recycled flexible content financially attractive to manufacturers.
Identifying Viable End-Use Applications
To solve the demand side of the equation, the Eunomia and Delterra researchers evaluated 40 potential end-use applications for household PE film. Crucially, the study filtered out markets that are already commercially saturated and viable in North America—such as plastic lumber, asphalt additives, and roof coverboards.
From the remaining pool, the authors identified eight high-potential end-use applications that share key technical compatibilities:
- Horticulture liners, trays, and plastic pots
- Rigid consumables
- Transit packaging pallets
- Rotational-molded items
- Industrial liners
- Impermeable construction membranes
- Agricultural heavy-duty covers
- Dark-colored trash bags
Technical Synergies and Volume Potential
What unites these eight applications is that they bypass the most stringent technical hurdles associated with food-contact sensitivity. Furthermore, these products are inherently tolerant of color variation, minor material imperfections, and varied resin compositions (such as commingled LDPE, LLDPE, and traces of HDPE).
Most impressively, these applications possess the capacity to incorporate recycled household PE film at rates ranging from 5% to 70%:
- Horticulture Liners & Pots: Capable of incorporating the highest percentage of recycled content, estimated at 30% to 70%.
- Industrial Liners, Construction Membranes, and Dark Trash Bags: Representing the true volume heavyweights, these three categories alone account for roughly 75% of the total potential demand, translating to approximately 600,000 tons per year.
In total, these eight targeted sectors could absorb approximately 800,000 tons of recycled PE film annually. The report emphasizes that while integrating household flexible plastics into film applications represents a far greater technical challenge than dumping them into thick-walled rigid items, film applications undeniably represent the largest volume opportunity for scaling recovery.
Official Statements and Industry Initiatives
As the supply chain mobilizes to meet these looming targets, collaborative coalitions are stepping forward to fund innovation, test sorting technologies, and establish operational processing pathways.
The Recycling Partnership’s Strategic Push
The Recycling Partnership has positioned itself at the vanguard of this movement. Having launched its dedicated Film & Flexibles Recycling Coalition in 2020, TRP has already deployed approximately $5 million across 19 distinct grant projects aimed at expanding end markets, improving collection methodologies, and purchasing advanced sortation equipment.
Katherine Huded, TRP’s Executive Director of Strategic Engagement, highlighted the coalition’s aggressive multi-stakeholder initiatives in recent commentary, focusing specifically on the groundbreaking CalFFlex Initiative. Developed in partnership with Delterra, the US Flexible Film Initiative, the Alliance to End Plastic Waste, and the Flexible Film Recycling Alliance, CalFFlex represents a concerted effort to scale operational capacity.
"Solving recycling’s toughest challenges takes all of us, and we’re encouraged by the industry momentum to work together across initiatives to drive the stronger demand pull essential to moving residential FFP recycling forward," Huded stated.
The CalFFlex initiative is currently supporting eight dedicated end-market grantees. More importantly, the program is actively dispatching "innovation test loads" of residential flexible film packaging (FFP) from California facilities directly to more than a dozen nascent and emerging mechanical end markets. These real-world trials are vital for testing how real-world, contaminated residential film performs in commercial manufacturing settings.
Pragmatism Over Ambition
Weighing in on the realistic challenges facing the sector, Sarah Edwards, North America Director and Private Lead at Eunomia, offered a sobering assessment of corporate ambition versus physical reality:
"The hardest part of building markets for recycled materials isn’t ambition—it’s honestly assessing what’s technically and economically feasible and being willing to follow the evidence where it leads."
Edwards’ perspective underscores a growing industry consensus: wishful thinking cannot replace rigorous engineering. Stakeholders must accept that residential flexible plastics cannot simply be forced into high-purity, food-contact packaging overnight. Success depends on strategically channeling materials into forgiving, non-food-contact applications where performance variances will not compromise product integrity.
Future Outlook: The Imperative for Proactive Adaptation
As the packaging industry looks toward the late 2020s and early 2030s, the writing is on the wall. The transition from a voluntary, fragmented recycling ethos to a heavily regulated, mandatory circular economy is accelerating rapidly.
The Danger of the "Wait-and-See" Approach
The Eunomia and Delterra report issues a stark warning to brand owners and manufacturers who continue to delay action: in today’s rapidly shifting economic and regulatory climate, adopting a "wait-and-see" posture is a recipe for obsolescence. Companies that delay testing recycled flexible materials in their supply chains until regulatory compliance deadlines are breathing down their necks will find themselves facing severe supply shortages, skyrocketing premium costs for compliant resins, and potential legal penalties.
Instead, progressive manufacturers are already initiating pilot programs, working alongside coalitions like TRP, and adjusting product specifications to accommodate post-consumer film. By experimenting today with recycled content in transit packaging, industrial liners, and horticultural pots, companies can iron out manufacturing kinks, secure reliable offtake agreements, and build resilient supply chains.
Conclusion
The journey to fix film and flexible plastics recycling is fraught with chemical complexities, collection bottlenecks, and economic hurdles. Yet, the convergence of aggressive EPR legislation, sophisticated market analysis, and unprecedented cross-industry collaboration has created a viable roadmap.
By aligning collection mandates with targeted end-market demand—specifically focusing on the eight high-potential non-food applications identified by Eunomia—the packaging industry has a genuine opportunity to convert its greatest environmental liability into a functional, circular asset. The tools are available, the pathways have been mapped, and the regulatory deadlines are ticking. The future of flexible packaging now depends entirely on the industry’s willingness to execute.