

Executive Overview
As the United Kingdom accelerates its transition toward a fully decarbonized electricity grid, energy regulators and government officials are turning to advanced "super battery" infrastructure to resolve the inherent variability of wind and solar generation. To support its overarching goal of achieving clean power by 2030 and net-zero emissions by 2050, the UK is backing a new class of Long-Duration Energy Storage (LDES) assets designed to hold and dispatch power over multi-hour, multi-day, or multi-week periods.
In a landmark policy move, Great Britain’s energy regulator, Ofgem, identified 16 priority LDES projects totaling 7.6 gigawatts (GW) of capacity under a pioneer revenue support mechanism known as the “cap-and-floor” scheme. These facilities—spanning pumped hydro, ultra-long lithium-ion installations, compressed-air storage, and advanced flow batteries—are engineered to buffer the grid against extended periods of low renewable output, colloquially known as dunkelflaute (German for "dark doldrums").
  +-----------------------------------------------------------------------+
  |              UK LDES CAP-AND-FLOOR SCHEME PIPELINE                    |
  +-----------------------------------------------------------------------+
  | 171 Initial Applications  ---------->  52.6 GW Requested Capacity     |
  |  77 Phase-2 Eligible      ---------->  28.7 GW Evaluated Capacity     |
  | 16 "Minded-to" Approved   ---------->   7.6 GW Provisionally Awarded   |
  +-----------------------------------------------------------------------+
Projections indicate that integrating high-capacity LDES infrastructure will dramatically optimize Great Britain’s power network, cutting energy system costs by more than £24 billion between 2030 and 2050. By absorbing surplus renewable energy that would otherwise be wasted during peak generation and discharging it during demand spikes, these assets are designed to lower consumer bills, curb fossil-fuel dependence, and reinforce national energy security.
Detailed Chronology & Policy Evolution
The framework governing Britain’s long-duration storage sector has evolved rapidly from early conceptual proposals to structured regulatory mandates and targeted innovation capital:
+-----------------------------------------------------------------------------------+
| CHRONOLOGY OF UK LDES POLICY & DEPLOYMENT                                         |
+-----------------------------------------------------------------------------------+
| 1980s      | Dinorwig Power Station ("Electric Mountain") opens in North Wales.   |
| 2015-2025  | Short-duration UK lithium-ion battery market expands from ~0 to >6 GW. |
| 2024       | UK Government announces landmark "Cap-and-Floor" revenue scheme.      |
| 2025       | Ofgem receives 171 LDES applications (52.6 GW); 77 proceed (28.7 GW).|
| May 2026   | UK's largest vanadium flow battery (21 MWh) opens in East Sussex.    |
| June 2026  | Ofgem releases "minded-to" decision backing 16 projects (7.6 GW).     |
| July 2026  | England World Cup match highlights grid surges (1.7 GW demand jump).  |
| Aug 2026   | Ofgem consultation closes; Innovate UK launches £10m ultra-long fund.|
+-----------------------------------------------------------------------------------+
Historical Baseline and Early Infrastructure
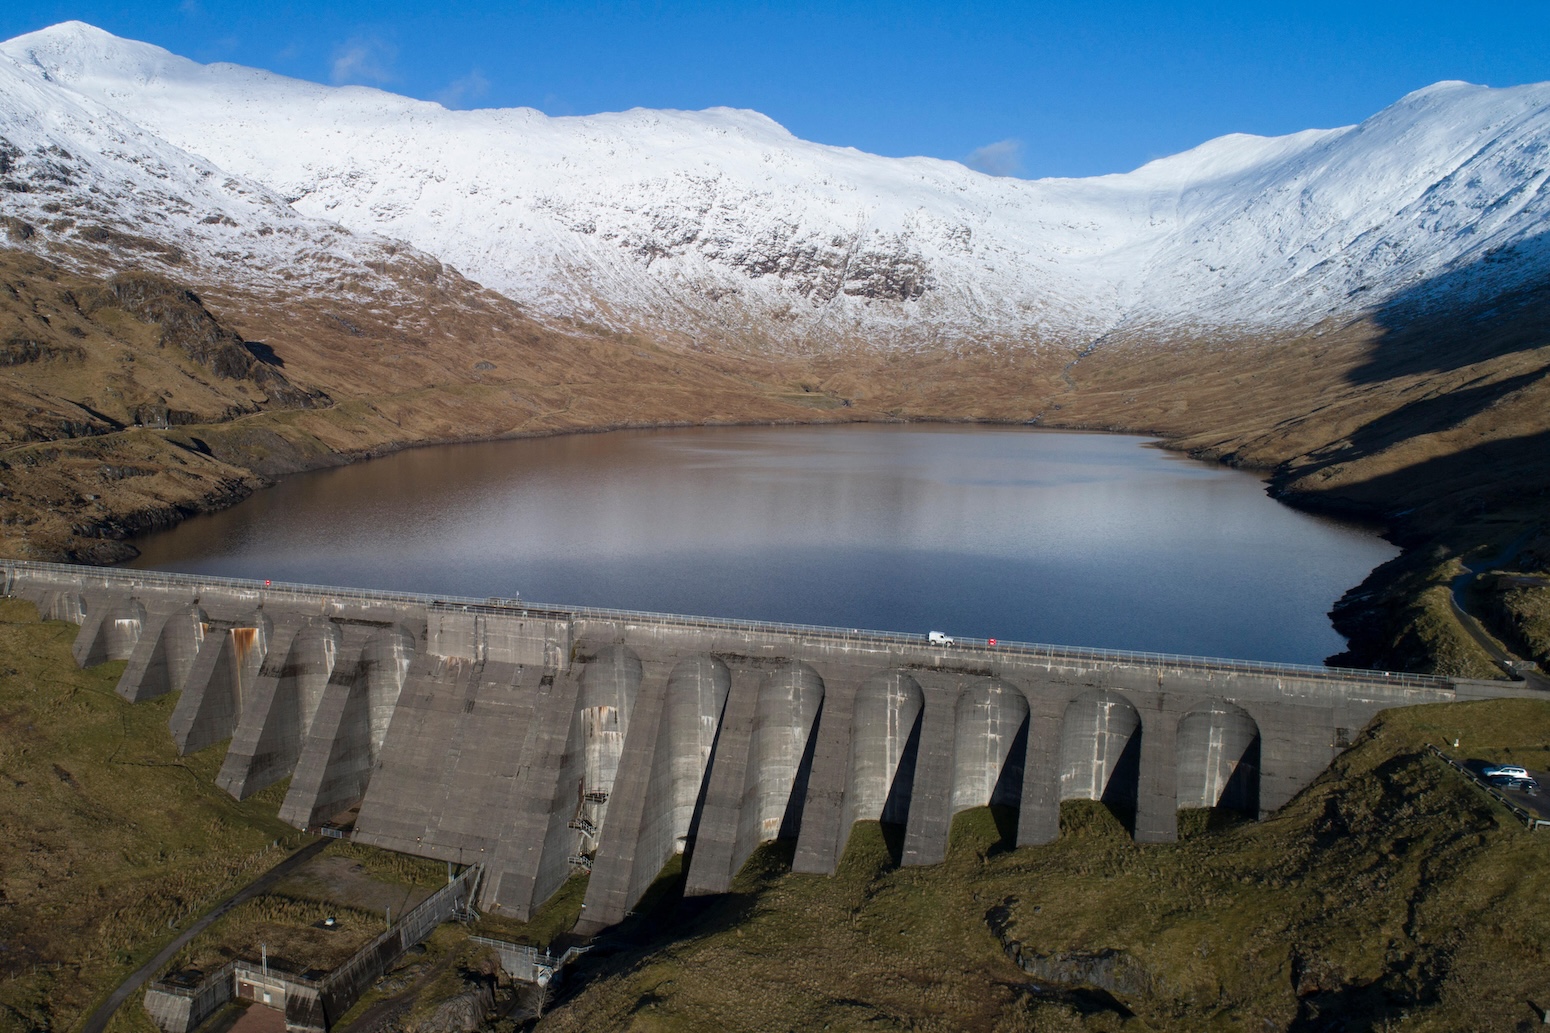
For four decades, Great Britain’s long-duration storage capacity remained locked at 2.8 GW, distributed across just four pumped-hydro assets located in Scotland and Wales. Chief among these is the 1,728 megawatt (MW) Dinorwig power station in North Wales ("the electric mountain"), commissioned in the 1980s to manage severe, instantaneous electricity demand swings.
The practical utility of rapid response storage was underscored on 1 July 2026, during England’s World Cup match against the Democratic Republic of Congo. Grid operators registered a demand spike of 1.2 GW at half-time and 1.7 GW at full-time—a surge equivalent to the combined baseline power demand of Glasgow and Leeds. Facilities like Dinorwig, alongside battery installations, were essential to preventing grid instability.
The Rise of Short-Duration Batteries
Between 2015 and 2025, Great Britain experienced a rapid boom in battery storage, growing from near zero to over 6 GW. However, these systems consisted almost entirely of lithium-ion batteries limited to 1–4 hours of continuous discharge. While effective for rapid frequency response and short intra-day balancing, they proved inadequate for addressing multi-day generation droughts.
The Cap-and-Floor Mechanism (2024–2026)
Recognizing that high upfront capital expenditures (CAPEX) hindered private financing for complex, multi-hour projects, the UK government introduced the cap-and-floor scheme in 2024. Administered by Ofgem and enabled by legislation within the Planning and Infrastructure Act, the model establishes:
- A Floor: Guarantees a minimum operational revenue threshold funded via electricity bills, de-risking capital investments for developers.
- A Cap: Caps maximum earnings, returning excess profits to consumers to keep the scheme broadly cost-neutral over time.
Competitive Window and Project Shortlisting
- 2025 Call for Projects: Ofgem received 171 applications totaling 52.6 GW of proposed storage.
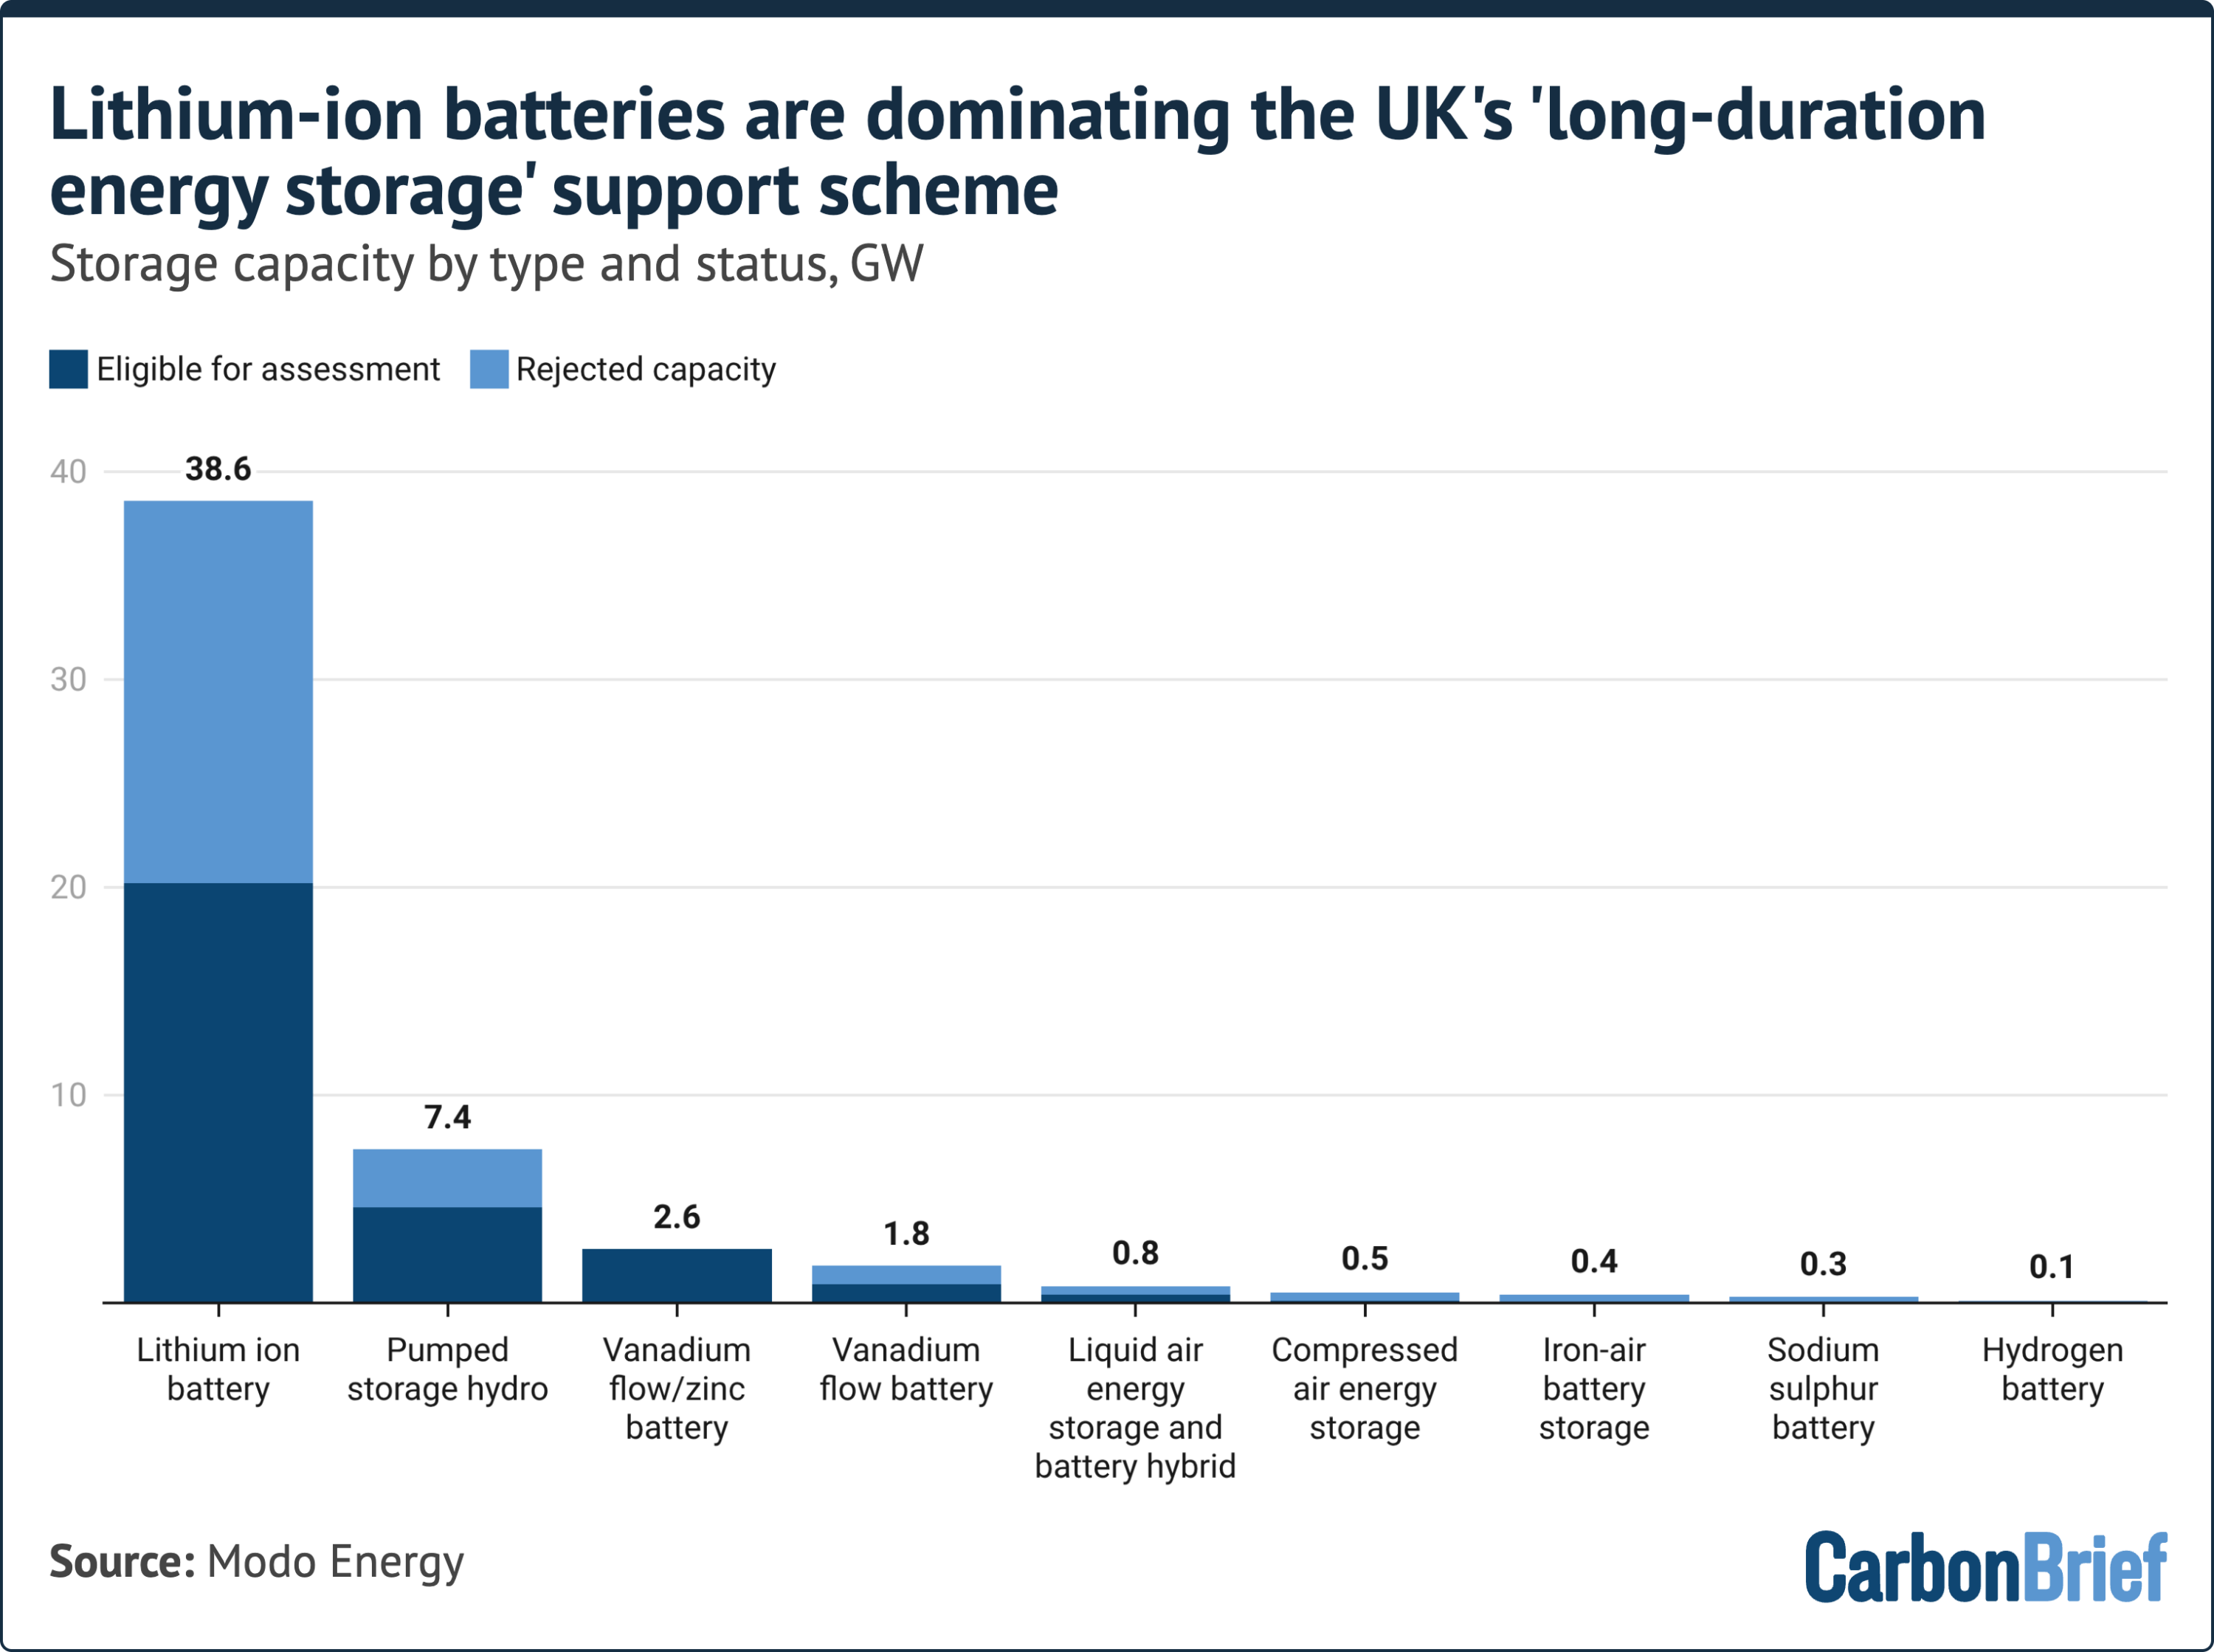
- Phase 2 Eligibility: Ofgem filtered the pool to 77 projects (28.7 GW) spanning nine distinct technology types. Lithium-ion variants made up over 20 GW of the shortlisted proposals.
- June 2026 "Minded-To" Allocation: Ofgem provisionally selected 16 flagship projects totaling 7.6 GW (with 4 GW targeted to be online by 2030).
- August 2026 Consultation & Innovation Push: Following Ofgem’s public consultation, Innovate UK launched an additional £10 million initiative (£3 million in initial phase-one grants ranging between £350,000 and £700,000) specifically targeted at demonstrating "ultra-long" storage technologies capable of discharging continuously for 100+ hours.
Supporting Context & Metrics
Key Technological Categories Compared
Energy storage technologies leverage different scientific principles to capture, hold, and dispatch power. The table below highlights the broad landscape of options available to grid planners:
| Technology Category | Mechanism | Storage Duration | Primary Strengths & Characteristics |
|---|---|---|---|
| Pumped Storage Hydro (PSH) | Mechanical | Hours to Days | Highly mature; long asset lifespans (>50 years); lowest capital cost per kWh over operational life. |
| Lithium-ion Batteries | Electrochemical | Hours to ~18 Hours | Rapidly falling CAPEX (-20% p.a.); high round-trip efficiency; expanding beyond standard 4-hr windows. |
| Compressed-Air Storage (CAES) | Mechanical | Hours to Days | Uses underground salt caverns or disused oil/gas wells to store high-pressure air that powers turbines. |
| Flow Batteries (e.g., Vanadium) | Electrochemical | Hours to Days | Chemical liquid stored in external tanks; decoupled energy/power capacity; minimal degradation. |
| Liquid Air Storage | Mechanical | Hours to Days | Compresses and cools air into liquid state; re-expansion drives generation turbines. |
| Hydrogen Salt Caverns | Chemical | Seasonal | Surplus electricity generates hydrogen via electrolysis; stored in deep salt caverns for seasonal dispatch. |
| Thermal Energy Storage | Thermal | Seasonal | Stores excess energy as heat in insulated media (e.g., gravel beds) to generate steam or hot water. |
Technical Analysis of the 16 Provisionally Approved Ofgem Projects
The 16 projects provisionally selected by Ofgem in June 2026 represent 7.6 GW of power capacity and tens of thousands of megawatt-hours (MWh) of energy capacity. Notably, 79% of total storage capacity is situated in Northern Scotland, strategically co-located behind transmission constraints to absorb trapped offshore wind power.
                  OFGEM APPROVED CAPACITY BY TECHNOLOGY
  +--------------------------------------------------------------------+
  | Pumped Hydro Storage (4 Projects)  =====> 3,900 MW (51.3%)        |
  | Extended Lithium-ion (10 Projects) =====> 3,630 MW (47.8%)        |
  | Vanadium-Zinc Flow (1 Project)     =====>    65 MW (0.8%)          |
  | Compressed Air Energy (1 Project)  =====>    50 MW (0.7%)          |
  +--------------------------------------------------------------------+
Detailed Project Breakdown:
| Project Name | Primary Technology | Location / Region | Power Capacity (MW) | Duration (Hours) | Total Storage (MWh) |
|---|---|---|---|---|---|
| Earba PSH | Pumped Storage Hydro | North Scotland | 1,800 | 15 | 27,000 |
| Coire Glas | Pumped Storage Hydro | North Scotland | 1,440 | 32 | 46,100 |
| Loch Kemp Storage | Pumped Storage Hydro | North Scotland | 660 | 22 | 14,500 |
| East Claydon Storage | Lithium-ion Battery | East England | 500 | 12 | 6,000 |
| Sundon Storage | Lithium-ion Battery | East England | 500 | 8 | 4,000 |
| Field Netherton | Lithium-ion Battery | North Scotland | 400 | 16 | 6,400 |
| Field New Deer | Lithium-ion Battery | North Scotland | 400 | 18 | 7,200 |
| Field Long Stratton | Lithium-ion Battery | East England | 400 | 16 | 6,400 |
| Springwell | Lithium-ion Battery | East Midlands | 400 | 11 | 4,400 |
| Drakelow (Innova) | Lithium-ion Battery | West Midlands | 385 | 9 | 3,500 |
| Field Rigifa | Lithium-ion Battery | North Scotland | 200 | 18 | 3,600 |
| Field Fyrish | Lithium-ion Battery | North Scotland | 200 | 17 | 3,400 |
| Ocker Hill BESS | Lithium-ion Battery | West Midlands | 145 | 8 | 1,200 |
| Thornton BESS 2 | Lithium-ion Battery | East Midlands | 100 | 11 | 1,100 |
| Frontier Legacy | Vanadium-Zinc Flow | North Wales | 65 | 8 | 500 |
| TeesCAES | Compressed Air | North-East England | 50 | 30 | 1,500 |
Note: In addition to utility-scale projects supported by the cap-and-floor scheme, smaller commercial deployments are advancing independently—such as the May 2026 installation in Uckfield, East Sussex, which co-located 90 vanadium flow batteries (21 MWh, 7-hour duration) with a 3 MW solar farm to supply 3,000 homes overnight.
Financial Mechanics and System Cost Reductions
The financial case for LDES rests heavily on mitigating grid balancing costs, which have grown significantly due to transmission bottlenecks.
+-----------------------------------------------------------------------------------+
| UK GRID BALANCING & CURTAILMENT COSTS (FY 2024–25)                                 |
+-----------------------------------------------------------------------------------+
| Total Grid Balancing Costs:      £2.7 Billion (~£40 added to average home bill)    |
| Transmission Constraint Penalty: £1.9 Billion (~£28 per household for curtailment) |
+-----------------------------------------------------------------------------------+
During periods of high wind output in Scotland, regional grid bottlenecks force system operators to pay Scottish wind farms to power down (curtailment) while simultaneously paying gas-fired power plants in England to spin up. LDES assets eliminate this inefficiency by storing excess localized generation for later dispatch.
Economic Savings Estimates Across Prominent Studies:
- Department for Energy Security and Net Zero (DESNZ) / Regen / LCP Delta Study (2023): Deploying 20 GW of LDES saves £16–51 billion in electricity system costs between 2030 and 2050 (central scenario estimate: £26 billion).
- LCP Delta (2025 Analysis): Building 20 GW of 8-to-12-hour pumped hydro yields direct net system savings exceeding £10 billion by 2050.
- Transition Finance Council Report: LDES integration reduces power system expenses by £7–13 billion annually between 2040 and 2050.
- Return on Investment (ROI): The Transition Finance Council estimates that every 1 GW of long-duration flexibility requires £2.0–2.5 billion in upfront CAPEX, but yields £0.5–1.0 billion in operational savings every year, providing net savings of £30–60 billion over a 25-year lifespan.
Official Statements & Industry Perspectives
Government and Regulatory Position
Speaking on Ofgem’s provisional scheme approvals, Energy Minister Michael Shanks highlighted the historical significance of the policy shift:
"Forty years after the country’s last pumped storage facility, this government is getting Britain building again… We are going further and faster in delivering the clean-power mission by rolling out a new generation of pumped-hydro storage and state-of-the-art batteries—making more of the clean, homegrown power we already produce, cutting waste, lowering bills and strengthening our energy security."
Industry and Expert Analysis
Definitions and Market Clarity
Sir Chris Llewellyn Smith, Emeritus Professor of Physics at the University of Oxford and lead author of a Royal Society report on electricity storage, noted ongoing debate regarding how LDES is defined across government bodies:
"[DESNZ] seems to describe it as including things which we would regard as some short duration or medium duration storage. It’s a big confusion… For us, long duration is stuff that can last not just into seasons, but into years and into decades."
Grid Dynamics and Wind Integration
George Martin, Principal for Power System Modelling at analytics firm LCP Delta, stressed the necessity of multi-day storage for wind-heavy grid architectures:
"[LDES is] really important for the system, particularly in a wind-driven system. You get more peaks and troughs in your renewable output and, while short duration can obviously help with that, with things like ‘dunkelflaute’, long-duration storage is what is needed."
Commenting on Ofgem’s evaluation methodology, Martin added:
"There’s going to be a lot of activity and a lot of responses to that consultation. I don’t expect the overall amount of capacity that’s been awarded to change, although they could increase it… But there might be some change in what projects end up getting approved as a result."
Evolving Battery Durations
Commenting on the performance of lithium-ion technology in securing approvals for up to 18-hour storage durations, Ed Porter, Director for Europe at data firm Modo Energy, observed:
"Lithium going far beyond 8 hours; that debate must surely be dead now."
International Perspective and Tech Diversity
Julia Souder, CEO of the global LDES Council, emphasized Britain’s pioneering role in regulatory design:
"The UK is leading the charge on technology diversity. We’re witnessing matching different LDES solutions to the real differences in market structure and country needs. But make no mistake: a handful of LDES technologies will do the heavy lifting over the next decade."
Academic and Research Perspectives
Dr. Jamie Speirs of the University of Strathclyde and Co-Director of the UK Energy Research Centre (UKERC), welcomed Innovate UK’s funding drive:
"By providing flexibility across hours, days and even seasons, LDES could enable a resilient, low-carbon electricity system—reducing curtailment, strengthening security of supply and ensuring that intermittent renewables can maximize their contribution to the grid in all conditions."
However, Seamus Garvey, Professor of Dynamics at the University of Nottingham, cautioned against over-relying on near-term short-duration assets:
"Energy storage will be required over many timescales and as we decarbonise further and further, the requirements for longer durations grow and grow. One key problem in my opinion is that because we are tending to buy into lots of short-duration stores now, we are actually removing pieces of market that could be accessible by longer duration stores and that is making the (already-difficult) problem of financing these stores ever more difficult."
Future Outlook & Strategic Roadmap
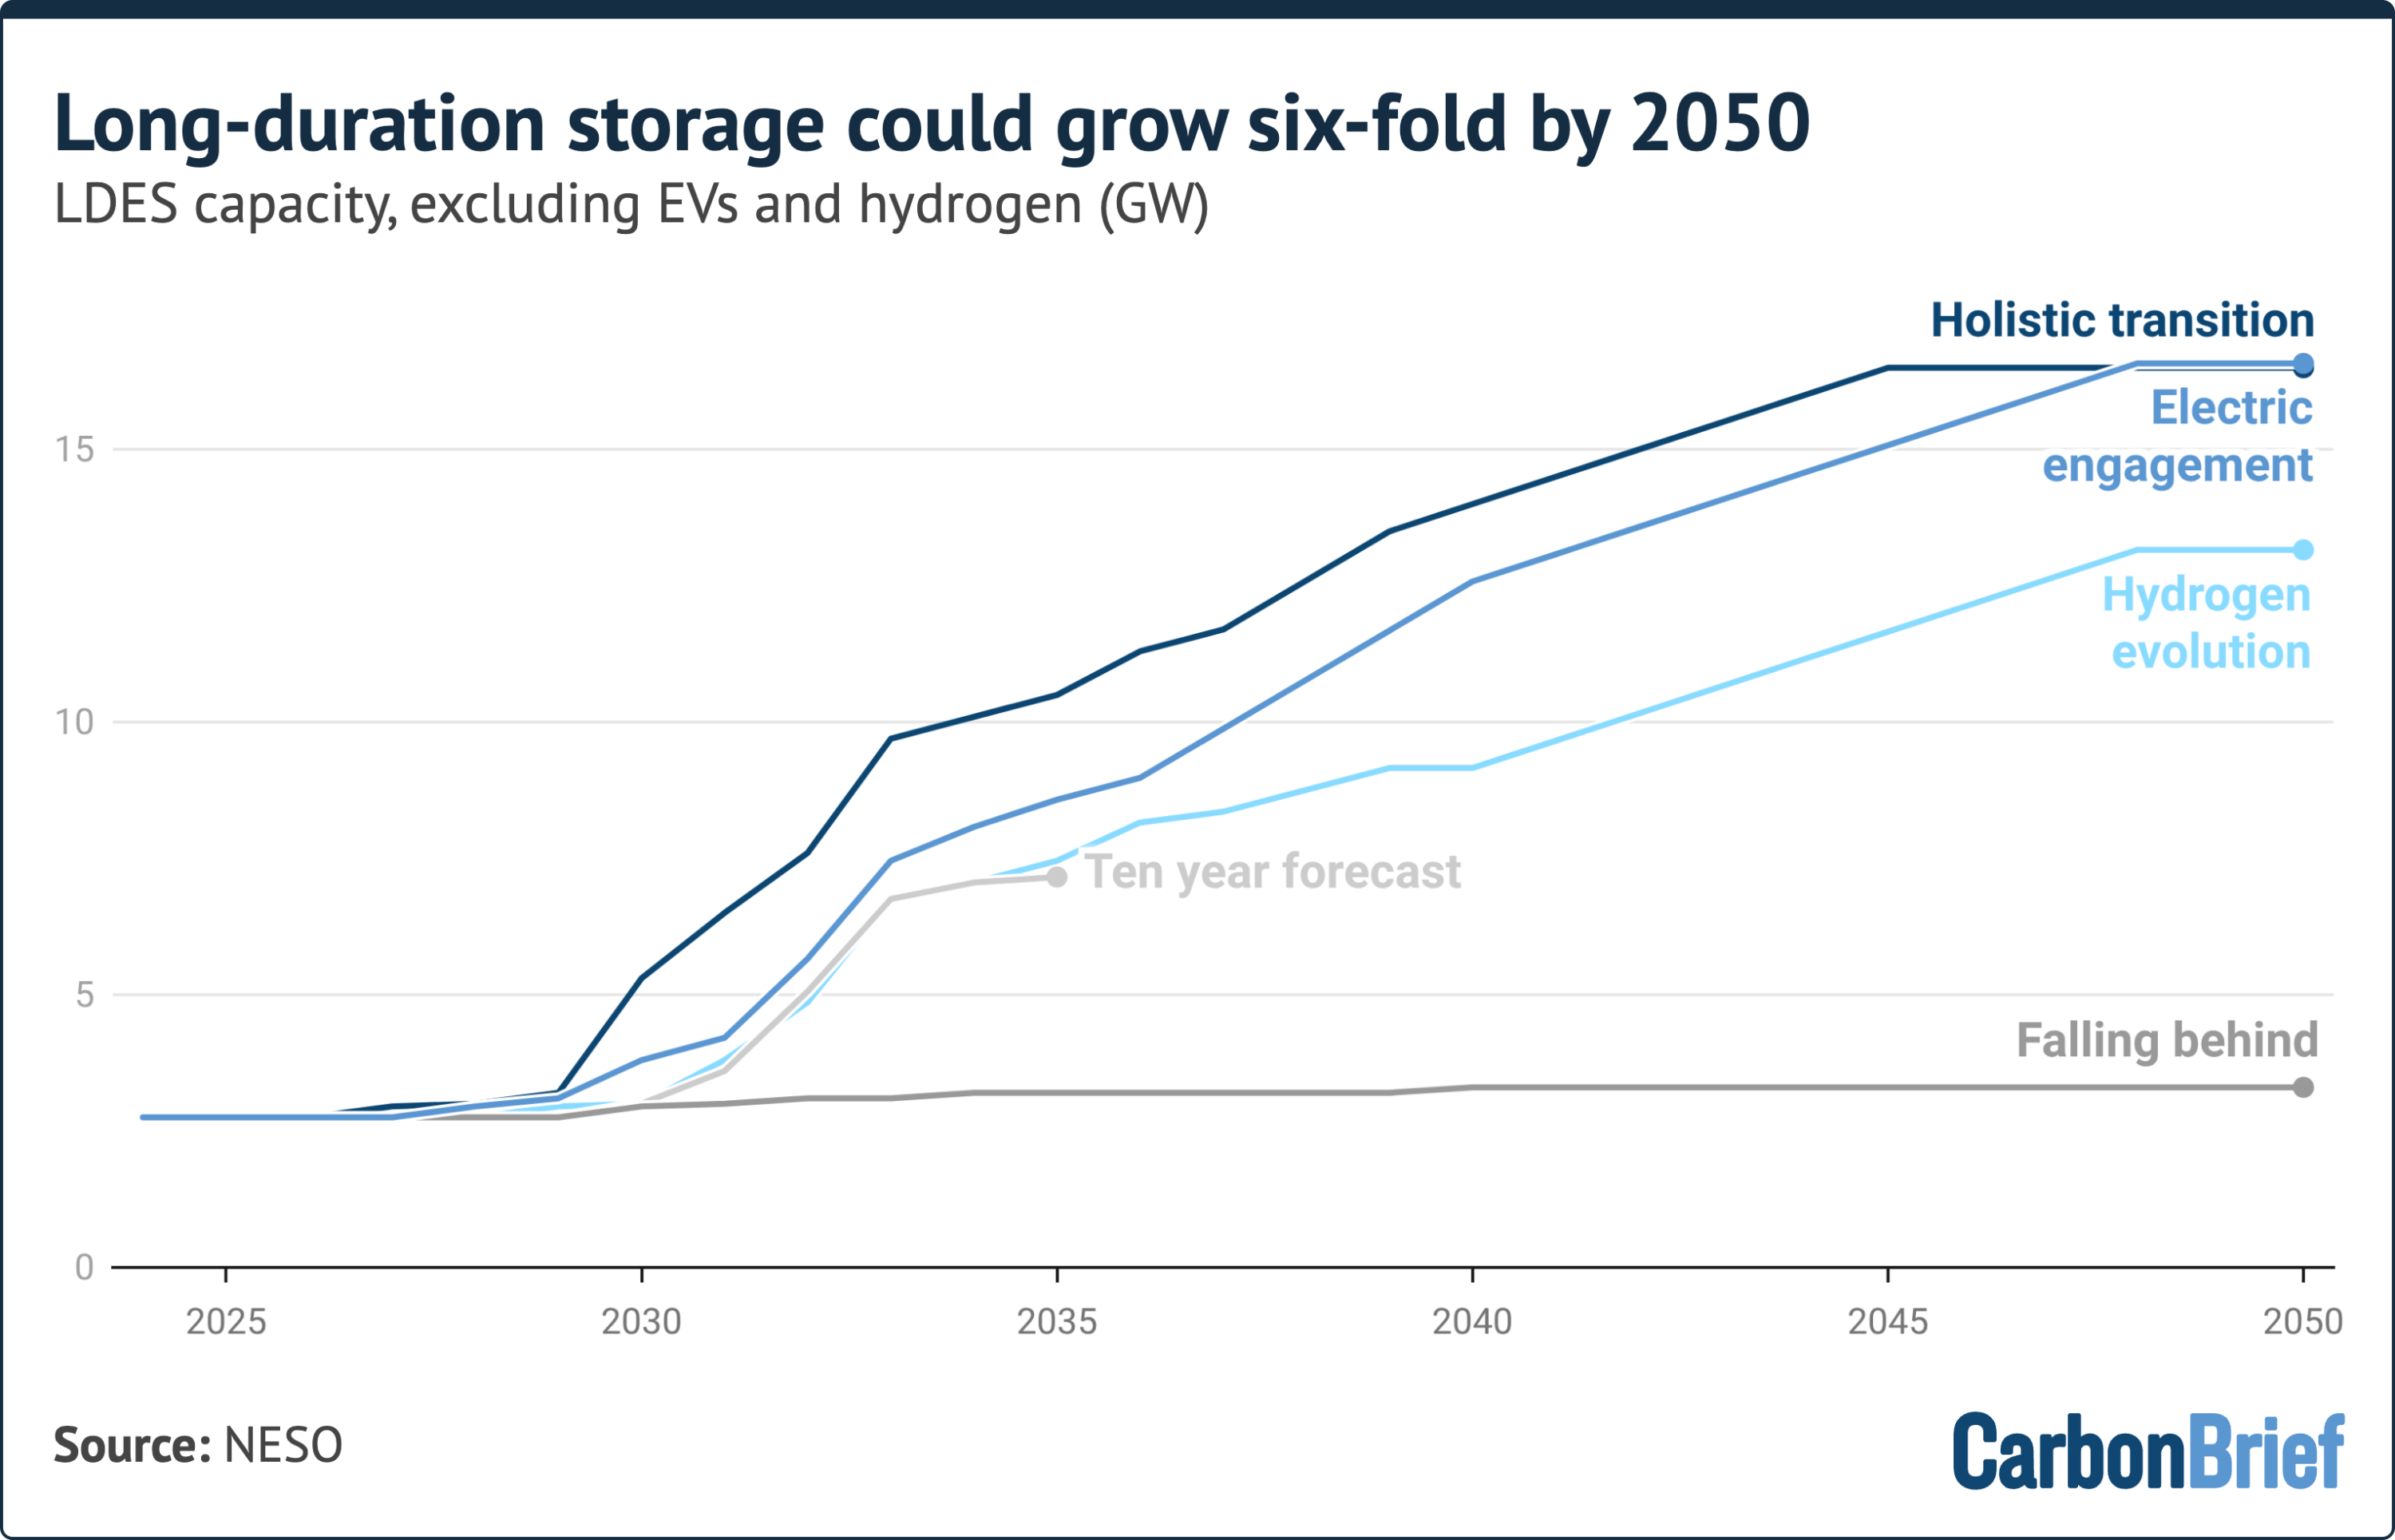
The integration of long-duration energy storage represents a structural shift in how Great Britain manages its power network. According to pathways outlined by the National Electricity System Operator (NESO), the nation’s energy storage trajectory is set to expand dramatically over the coming decades:
  +--------------------------------------------------------------------+
  |      NATIONAL ELECTRICITY SYSTEM OPERATOR (NESO) LDES TARGETS      |
  +--------------------------------------------------------------------+
  | Current Baseline Capacity (2025):                  2.8 GW          |
  | Clean Power Action Plan Target (2030):            4.0 - 6.0 GW      |
  | NESO Future Energy Scenarios Target (2030):       3.8 - 5.3 GW      |
  | NESO Long-Term Net-Zero Target (2050):           13.2 - 16.6 GW     |
  +--------------------------------------------------------------------+
Strategic Milestones Ahead
-
Short-Term Delivery (2026–2030):
- Ofgem will finalize project determinations following the August 2026 consultation close.
- Developers will move to financial close, backed by cap-and-floor revenue guarantees, aiming to bring at least 4 GW of new LDES online by 2030.
- Short-duration battery capacity will simultaneously scale to 23–27 GW, complementing LDES facilities.
-
Medium-Term Integration (2030–2040):
- PSH mega-projects like Coire Glas (1.44 GW / 46.1 GWh) and Earba (1.8 GW / 27 GWh) will complete long construction cycles, bringing massive multi-day reserve capacity online.
- Hybrid battery installations—combining long-duration lithium formulations with flow batteries and compressed-air sites—will smooth localized regional transmission bottlenecks across Scotland and Northern England.
-
Long-Term Grid Decarbonization (2040–2050):
- LDES capacity is projected to reach up to 16.6 GW, with multi-day and seasonal storage (including clean hydrogen stored in underground salt caverns) playing a central role.
- Systemic balancing costs will plummet as gas-fired backup generation is phased out, saving consumers tens of billions of pounds and providing a repeatable blueprint for grid decarbonization worldwide.



